Beyond Investment Management: Why Your Wealth Needs a Coordinated Financial Strategy
Key takeaways
1\. Coordinated financial planning brings investments, pensions, retirement income, tax considerations and family wealth together into a coherent long-term strategy.
2\. Investment performance is only part of financial success. Effective planning ensures your wealth supports your lifestyle, financial security and personal objectives.
3\. Professional coordination matters. An experienced financial adviser can help ensure decisions involving accountants, solicitors and other specialists are aligned with your wider financial strategy.
4\. Cash-flow modelling supports better decisions. It helps assess retirement sustainability, explore different financial scenarios and understand the potential consequences of important choices.
5\. Financial planning is an ongoing process. Regular reviews ensure your strategy evolves alongside changes in your circumstances, priorities, legislation and financial needs.
Beyond Investment Management: Why Your Wealth Needs a Coordinated Financial Strategy
Managing substantial wealth can become surprisingly complicated.
You may have built a successful business, accumulated significant investments, acquired property, established pension arrangements and created financial security for your family.
Yet the more successful you become, the more difficult it can be to ensure that every element of your finances is working together.
Your accountant may handle your tax returns. Your solicitor looks after legal matters. Your investment adviser manages your portfolio. Your pension provider administers your retirement benefits.
Each may be doing an excellent job.
But who is looking at the whole picture?
Who is ensuring that decisions about investments, retirement, taxation, borrowing, business interests and family wealth form part of a coherent long-term strategy?
This is where strategic financial planning becomes particularly valuable.
My approach is to provide an overarching perspective on my clients’ financial circumstances: helping them make important decisions, coordinate specialist advice and structure their wealth around their long-term objectives.
It is about considerably more than selecting investments or reviewing portfolio performance.
It is about ensuring that the different elements of your finances support one another, rather than operating independently.
Why Successful Individuals Need More Than Investment Management
Investment management is important. In many cases, it represents a substantial part of the financial planning relationship.
But investment performance is not the same as financial success.
Consider an individual with £3 million of investable assets, several pensions, a valuable property and plans to retire within five years.
An investment manager may construct a well-diversified portfolio and deliver appropriate investment performance.
But that alone does not answer some of the most important questions:
- How much can the individual afford to spend during retirement without placing their long-term security at unacceptable risk?
- Which accounts and pensions should fund their expenditure, and in what sequence?
- What tax liabilities might arise when accessing different assets?
- Should surplus wealth be retained, gifted to family members or structured differently?
- What happens if the individual dies unexpectedly or becomes unable to make financial decisions?
- How should the strategy change if they relocate overseas, sell a business or receive an inheritance?
These questions cannot be answered by looking at investment returns alone.
They require a broader assessment of wealth, taxation, family circumstances, risk and long-term objectives.
I regularly use cash-flow modelling to examine how different decisions might affect a client’s financial future, including the consequences of retiring earlier, spending more, making gifts or experiencing weaker investment returns.
The purpose is not to predict the future with certainty. It is to understand the range of possible outcomes and make better-informed decisions today.
Investment Management and Strategic Financial Planning: What’s the Difference?
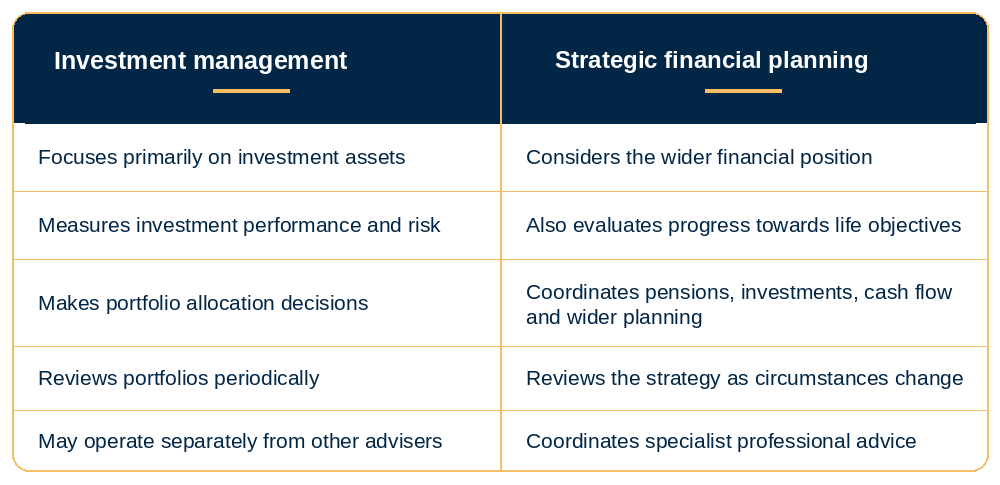
Investment management concentrates principally on constructing, managing and reviewing investment portfolios.
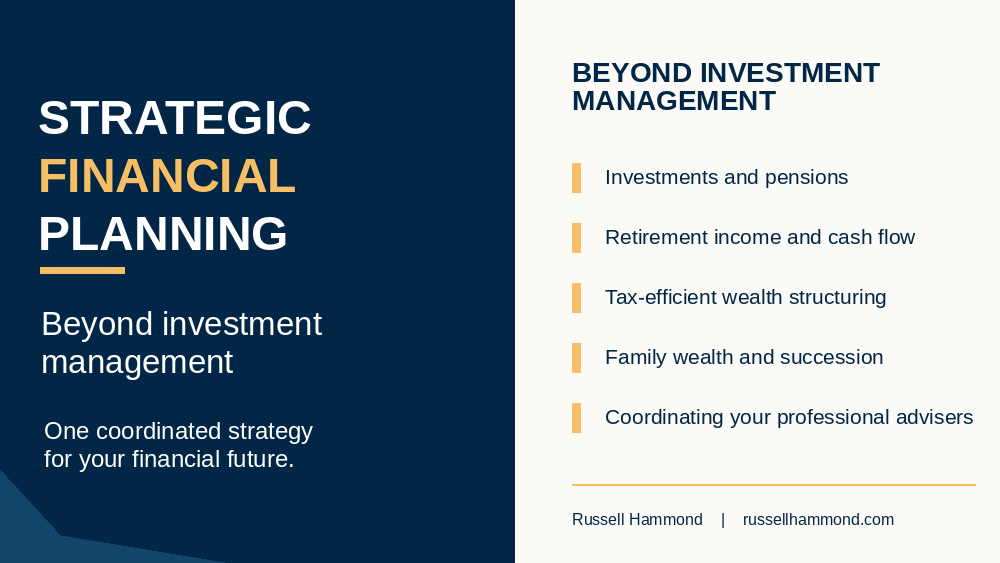
Strategic financial planning considers how those investments fit into a wider financial strategy, alongside pensions, retirement income, tax-efficient structuring, property, borrowing and family wealth.
The two are complementary rather than competing services.
In my experience, investment decisions become considerably more meaningful when they are connected to a clearly defined financial objective.
A portfolio’s performance matters, but so does what that portfolio enables its owner to achieve.
The Importance of Having Someone Who Sees the Whole Picture
A successful business with substantial assets, financial commitments and long-term objectives would ordinarily have someone overseeing its financial strategy.
That responsibility often belongs to the Chief Financial Officer.
A good CFO does not personally perform every specialist task. Instead, they understand the organisation’s overall financial position, anticipate future requirements and ensure that individual decisions support the wider strategy.
I believe there is considerable value in applying a similar principle to personal wealth.
For many successful individuals and families, their personal finances can become every bit as complicated as those of a business.
There may be investments held across multiple institutions, pensions with different benefits and withdrawal rules, property, business interests, inheritance considerations and family commitments.
The challenge is not simply managing each arrangement competently.
It is ensuring that the arrangements work together.
As a Chartered Financial Planner, my role is to help identify the decisions that matter, examine how they interact and coordinate appropriate professional expertise where required.
This does not mean replacing your accountant, solicitor or other specialist advisers. Quite the opposite: their individual expertise is often essential to creating an effective financial strategy.
The objective is to ensure that important decisions are not made in isolation.
The Key Elements of a Coordinated Financial Strategy
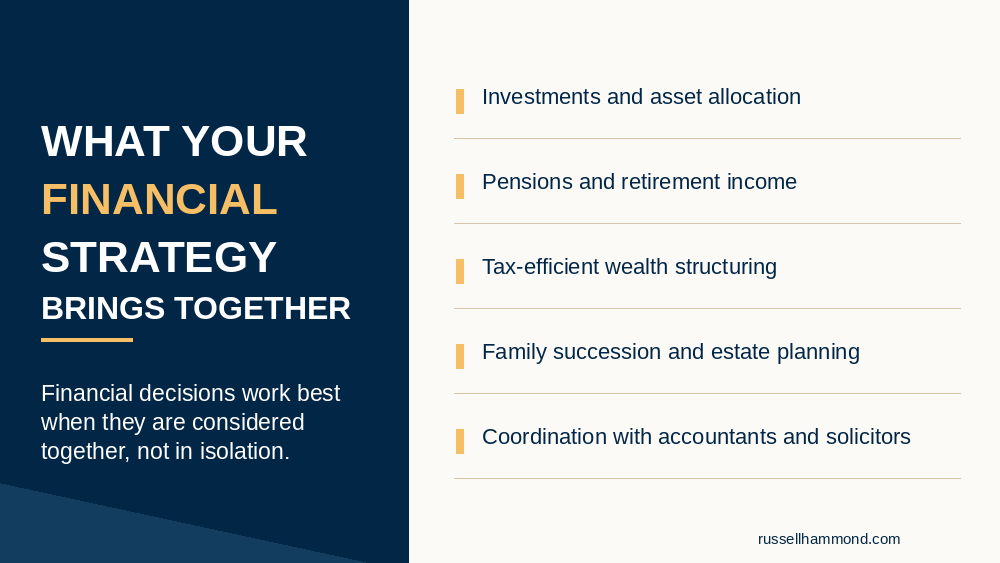
There is no single formula for managing substantial or complex wealth.
The appropriate priorities will depend on your circumstances, the nature of your assets, your family and what you are ultimately trying to achieve.
However, there are several important areas that I would ordinarily consider as part of an ongoing financial planning relationship.
Investment Strategy and Wealth Management
Investment portfolios should be constructed around your objectives, time horizon, capacity for risk and need for liquidity.
My investment approach is evidence-based, emphasising asset allocation, diversification, appropriate risk management and controlling unnecessary costs.
Where assets are held across different accounts, pensions and investment structures, I consider the combined allocation rather than treating each portfolio in isolation.
This can help identify unintended concentrations, overlapping investments, excessive costs or inconsistent investment strategies.
Retirement Income and Cash-Flow Planning
For many clients, the transition from accumulating wealth to drawing an income represents one of the most significant financial decisions of their lives.
The objective changes from growing accumulated wealth to ensuring that available resources can support their desired lifestyle over time.
I help clients evaluate retirement income needs, pension withdrawal options, the appropriate balance between growth and defensive assets, and the interaction between pensions, cash reserves and other investments.
Cash-flow modelling can help assess whether planned expenditure is sustainable and how different retirement choices may affect long-term financial security.
For clients already enjoying retirement, the emphasis may be less on accumulating additional wealth and more on making effective use of what they have already built.
Tax-Efficient Wealth Structuring
How investments and pensions are held can be just as important as the investments themselves.
The appropriate combination of pensions, ISAs, general investment accounts, investment bonds and other structures will depend on individual circumstances.
I consider tax efficiency as part of the wider planning strategy, including how assets may be accessed, transferred or passed to beneficiaries.
Where specialist tax advice is required, I coordinate with suitably qualified tax professionals rather than attempting to replace their role.
Family Wealth and Succession
Wealth often has a purpose beyond the individual who accumulated it.
You may wish to help children purchase homes, fund education, provide for vulnerable family members or transfer assets to future generations.
The challenge is to balance generosity with your own financial security and the need to retain sufficient resources throughout retirement.
I help clients examine the financial consequences of gifting, inheritance planning and succession arrangements, working alongside legal and tax professionals where appropriate.
Borrowing, Mortgages and Lombard Lending
Borrowing can also form an important part of a wider financial strategy.
Whether you are arranging a residential mortgage, financing a property purchase or considering Lombard lending secured against an investment portfolio, the key is to ensure that any borrowing complements your overall financial position.
I help clients assess how different financing arrangements fit alongside their investments, cash flow, liquidity requirements and long-term objectives.
This includes considering borrowing costs, repayment flexibility, interest rate exposure and the risks associated with using investments as collateral, particularly where market falls could trigger additional security requirements or forced asset sales.
Where specialist lending advice is required, I can coordinate with appropriate mortgage brokers, private banks and lending specialists.
International and Cross-Border Financial Planning
For internationally connected individuals, financial decisions can become particularly complicated.
A pension established overseas, a property in another country, an investment bond or a planned change of tax residence may introduce issues that are not apparent when considering each arrangement separately.
My experience advising internationally mobile clients is particularly relevant where UK financial planning interacts with overseas assets, pension arrangements, residency or succession rules.
International considerations require careful examination of the relevant jurisdictions and, where necessary, coordination with locally qualified specialists.
Coordination Between Professional Advisers
An often-overlooked part of effective financial planning is ensuring that the right professionals are involved in the right decisions.
Your accountant may be preparing for one tax outcome while your investment arrangements are structured with a different objective in mind.
Your estate planning may have been prepared years before significant changes to your assets or family circumstances.
By taking an overarching view, I can identify where decisions should be considered together and help ensure that relevant advisers are working towards the same objectives.
I remain your financial planning adviser and central point of contact for the strategy, while each specialist retains responsibility for their own professional advice.
Who Benefits Most From Strategic Financial Planning?
Coordinated financial planning is particularly valuable when financial circumstances have become too complex to manage comfortably through a series of unrelated decisions.
In my experience, the people who benefit most are not necessarily those with the largest investment portfolios.
They are those whose financial decisions have become increasingly consequential.
Individuals Approaching or Enjoying Retirement
Retirement is rarely just about choosing when to stop working.
It involves deciding how to finance a desired lifestyle, how much investment risk to retain, how to structure withdrawals and what to do with wealth that may ultimately be left to others.
Having a coherent retirement income strategy can help turn accumulated financial assets into greater confidence about the choices available.
Business Owners and Entrepreneurs
Running a successful business creates financial opportunities, but also introduces complexity.
Business income, investments, company pension contributions, eventual succession and potential business sales may all interact.
For business owners, personal financial planning should be coordinated with commercial objectives, available liquidity and the eventual transition from business ownership to personal financial independence.
Senior Executives and Professionals
High-earning professionals may accumulate pensions, employee share awards, deferred compensation, investments and property over the course of their careers.
Their financial circumstances can be particularly sensitive to changes in employment, earnings, tax rates or retirement plans.
An integrated strategy can help ensure that wealth accumulated during high-earning years is managed appropriately for the longer term.
Internationally Mobile Individuals and Families
Moving between countries can change the rules governing taxation, pensions, inheritance and investment arrangements.
For people who have spent much of their careers overseas, returning to the UK may require a substantial reassessment of their financial affairs.
Individuals With Substantial or Complex Family Wealth
As wealth grows, questions about family support, inheritance, trusts, property and succession can become more important.
The objective is not necessarily to create more complicated financial structures.
Often it is quite the opposite: to simplify existing arrangements, clarify responsibilities and ensure that wealth is managed in a way that reflects personal and family priorities.
Good Financial Planning Should Reduce Complexity, Not Create It
A point that is sometimes overlooked in wealth management is that complexity is not automatically a sign of sophistication.
Having several investment platforms, multiple advisers and a collection of financial products does not necessarily improve financial outcomes.
In fact, unnecessary complexity can make it more difficult to understand your financial position, assess costs or make timely decisions.
Part of my role is to identify when existing arrangements can be simplified.
That might involve consolidating investments, reviewing outdated pensions, reducing overlapping holdings, establishing clearer reporting or determining whether complex structures still serve a useful purpose.
The objective is not consolidation for its own sake. Sometimes retaining separate arrangements is sensible because they offer valuable benefits, diversification or different tax treatment.
The important question is whether every element of the financial structure has a clear purpose.
A well-organised financial strategy should make your affairs easier to understand, not more difficult.
How I Develop and Maintain Your Financial Strategy
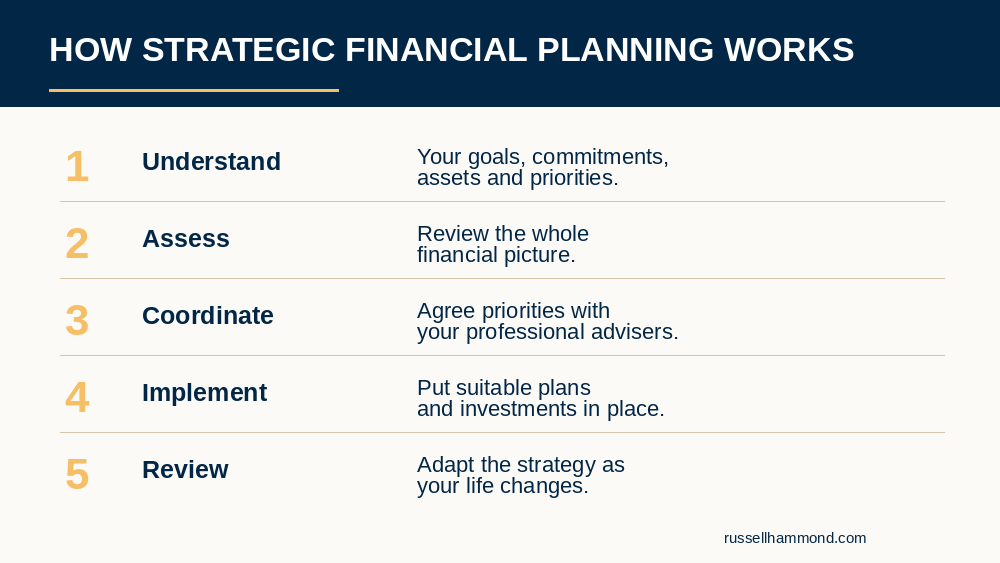
I approach strategic financial planning as an ongoing relationship rather than a one-off exercise.
The work begins with understanding your current position, but its value continues as your circumstances and objectives evolve.
Understanding What Matters to You
Before making financial recommendations, I want to understand your wider circumstances.
That includes your existing assets and liabilities, income, expenditure, family commitments, risk preferences and future plans.
Perhaps you want to retire early, reduce working hours, move abroad, help your children financially or simply feel more comfortable spending the wealth you have accumulated.
These objectives provide the context for the financial strategy.
Assessing Your Existing Arrangements
The next step is to assess how your finances are currently organised.
I consider pensions, investments, cash reserves, existing financial structures and the wider planning position.
Where appropriate, financial modelling helps establish whether existing arrangements are aligned with your objectives and identifies areas that may require attention.
Developing and Coordinating Your Strategy
I then develop suitable recommendations and establish which actions should take priority.
Some decisions may involve changes to investments or pensions. Others may require input from your accountant, solicitor or another specialist.
Where appropriate, I help coordinate that input so decisions are considered in the context of your overall objectives.
Implementing Agreed Recommendations
A financial strategy only becomes valuable when appropriate actions are taken.
I help arrange and oversee the implementation of recommendations within the scope of my advice, working with relevant providers and professional advisers as necessary.
Not every recommendation requires changing a product or transferring an investment.
Sometimes the correct decision is to retain an existing arrangement.
Reviewing and Adapting Over Time
Your financial circumstances will change. So will markets, legislation, family requirements and your own priorities.
Regular reviews help ensure the strategy remains appropriate.
For my ongoing clients, I normally work to a structured six-monthly review cycle, supplemented by contact when significant circumstances or decisions require attention.
The objective is to build an ongoing advisory relationship in which important decisions benefit from a detailed understanding of your financial history and long-term objectives.
The Value of a Long-Term Financial Planning Relationship
There is a considerable difference between receiving financial advice when you ask for it and having an ongoing adviser who understands your circumstances in depth.
The longer an advisory relationship continues, the more context the adviser can develop.
Decisions about your finances are no longer considered in isolation. They can be assessed against your previous choices, your current financial position and the objectives you have discussed over time.
That continuity can be particularly valuable during major life events.
A business sale, inheritance, change of residence, retirement decision or family bereavement can create several interconnected financial issues.
Instead of approaching each question without an established strategy, you have someone familiar with your circumstances who can help determine what requires attention and which specialists should be involved.
This is the aspect of financial planning that I find especially rewarding.
Over more than 20 years as a financial adviser, I have come to appreciate that the most valuable client relationships are rarely defined by a single investment recommendation.
They develop through years of discussion, planning, implementation and adjustment as clients move through different stages of their lives.
It is that longer-term perspective that I aim to bring to every ongoing client relationship.
Is Coordinated Financial Planning the Same as a Family Office?
There is some overlap, but the two services are not identical.
A traditional family office may provide extensive administrative, investment, reporting, governance and other services for a family with substantial wealth, often involving a dedicated team.
Strategic financial planning can provide some of the oversight and professional coordination that makes a family-office relationship valuable, without necessarily requiring that level of infrastructure.
For clients whose needs justify a more extensive family-office structure, additional specialist services may be appropriate.
My role is primarily one of strategic financial planning and investment advice, together with coordination of relevant professional input.
It is not a promise to provide every legal, tax, accounting or administrative service personally.
What Should You Expect From a Coordinated Financial Strategy?
Ultimately, I believe an effective financial planning relationship should help you achieve three things.
A clearer understanding of your position. You should understand how your wealth is organised, what it can reasonably support and which decisions deserve attention.
Better-informed financial decisions. Investments, pensions, taxation, borrowing and family objectives should be considered together so that decisions in one area do not unintentionally undermine another.
A strategy that evolves with you. Your financial arrangements should be reviewed and adjusted as your circumstances, priorities and the wider environment change.
None of these outcomes can eliminate uncertainty or guarantee investment performance.
But they can improve the structure and consistency of financial decision-making.
And for someone who has spent decades accumulating wealth, that can be every bit as valuable as the individual investment decisions made along the way.
Your Wealth Should Support Your Life
Successful financial planning is not simply about accumulating the largest possible portfolio.
It is about understanding what your wealth is for.
For some, that means financial independence and the ability to stop working.
For others, it means supporting family, pursuing interests, relocating, giving money away or creating a lasting legacy.
My approach to strategic financial planning is to connect those objectives with the financial decisions required to pursue them.
That means looking beyond individual pensions, investment accounts and financial products to understand how everything fits together.
The ultimate purpose is simple: to help you make informed decisions about your wealth, with the benefit of a consistent, long-term financial strategy.
Your financial arrangements should serve your ambitions and priorities, not dictate them.
Frequently Asked Questions
What is strategic financial planning?
Strategic financial planning is a comprehensive approach to managing wealth that considers investments, pensions, retirement income, tax efficiency, family circumstances and long-term objectives together. It helps ensure individual financial decisions form part of a coherent overall strategy.
How is strategic financial planning different from investment management?
Investment management focuses primarily on constructing and managing portfolios. Strategic financial planning examines how those portfolios support broader objectives, including retirement income, financial independence, tax-efficient withdrawals, inheritance planning and other significant decisions.
Why is coordinated financial planning important for wealthy individuals?
As wealth accumulates across multiple accounts, pensions, properties and other assets, financial decisions become increasingly interconnected. Coordinated planning helps identify risks, improve efficiency and ensure different arrangements support the same long-term objectives.
Can a financial planner work with my accountant and solicitor?
Yes. With your agreement, a financial planner can coordinate with accountants, solicitors and other professionals to help ensure financial recommendations are consistent with your wider strategy. Each professional remains responsible for advice within their own area of expertise.
How often should a financial strategy be reviewed?
Financial strategies should be reviewed regularly and when important circumstances change. I normally conduct structured six-monthly reviews with my ongoing clients, alongside additional discussions when decisions involving retirement, investments, taxation, inheritance or other significant matters require attention.
Continue reading
Want to Change Your RL360 Adviser or Get a Second Opinion?
If you hold an RL360 investment bond and are considering changing financial adviser, you’re not alone. Many RL360 policyholders originally established their bond years ago, often whilst living [...]
Momentum QROPS: A Guide to Your Pension, Changing Adviser and Retirement Planning
If you hold a Qualifying Recognised Overseas Pension Scheme (QROPS) with Momentum Pensions, you may have established your pension many years ago, perhaps while living and working overseas. Since [...]
Thinking About Changing Your Utmost Adviser?
Thinking About Changing Your Utmost Adviser? If you hold an Utmost International investment bond and feel that your existing advice relationship is no longer meeting your expectations, it [...]