Transfer a Gibraltar QROPS to a UK SIPP: Rules, Tax and Drawdown
Key takeaways
-
Gibraltar QROPS do not generally offer the same flexi-access drawdown flexibility as UK SIPPs.
-
Taxable Gibraltar QROPS pension withdrawals are ordinarily subject to 2.5% Gibraltar income tax.
-
Transferring a Gibraltar QROPS to a UK registered pension is generally possible without the 25% overseas transfer charge.
-
Momentum and Sovereign Gibraltar transfers may require additional trustee documentation, including tax advice.
-
The transfer decision should consider tax residence, existing benefits, charges and the wider retirement strategy.
If you have a pension held in a Gibraltar Qualifying Recognised Overseas Pension Scheme (QROPS), you may be surprised to discover that the rules governing withdrawals are quite different from those applying to a UK Self-Invested Personal Pension (SIPP).
In particular, Gibraltar QROPS do not provide the same flexi-access drawdown arrangements available through modern UK pensions. There is also generally a 2.5% Gibraltar income tax charge on taxable pension withdrawals, which can introduce another layer of complexity.
For individuals who have returned to the UK, or who are planning to return, transferring a Gibraltar QROPS to a UK SIPP can therefore be an attractive option.
I have been involved in arranging transfers from Gibraltar QROPS providers, including arrangements administered by Momentum and Sovereign. While these transfers are certainly possible, there are a number of technical and administrative considerations that need to be handled properly.
Why Gibraltar QROPS Can Be Restrictive
Gibraltar was historically a popular destination for British expatriates transferring their UK pensions overseas.
Its QROPS arrangements offered internationally mobile individuals a way of holding their retirement savings outside the UK, potentially benefiting from different local pension rules.
However, the flexibility introduced to UK pensions in April 2015 was not replicated in Gibraltar.
Unlike a UK SIPP offering flexi-access drawdown, Gibraltar QROPS generally operate under rules that require the majority of the fund to remain available to provide retirement income.
This can be frustrating for individuals who want more control over when and how they access their retirement savings.
No UK-Style Flexi-Access Drawdown
With a modern UK SIPP, flexi-access drawdown allows you to decide how much income to withdraw and when to withdraw it, subject to the applicable tax rules.
You might take a relatively large withdrawal in one year, reduce your pension income the following year, or take no income at all.
Gibraltar QROPS do not generally permit this level of flexibility.
Although income drawdown may be available, withdrawals are ordinarily restricted by limits designed to preserve the pension fund for retirement income.
For someone seeking to coordinate pension withdrawals with other investments, cash reserves or retirement income sources, this lack of flexibility can be a significant disadvantage.
The 2.5% Gibraltar Tax on Pension Withdrawals
Another important difference is Gibraltar’s taxation of pension income.
Taxable income distributions from Gibraltar QROPS are generally subject to Gibraltar income tax at 2.5%, ordinarily deducted when the payment is made.
For example, a £40,000 taxable pension income withdrawal could result in £1,000 of Gibraltar tax.
Importantly, the 2.5% Gibraltar tax is not necessarily the total tax payable.
If you are UK tax resident, your pension income may also be subject to UK income tax. The interaction between Gibraltar withholding, UK taxation and any available double taxation relief needs to be considered carefully.
Transferring the pension to a UK SIPP can remove the ongoing Gibraltar pension payment process from future withdrawals, although the tax treatment of your UK pension income will then follow the applicable UK rules.
Gibraltar QROPS vs UK SIPP: What’s the Difference?
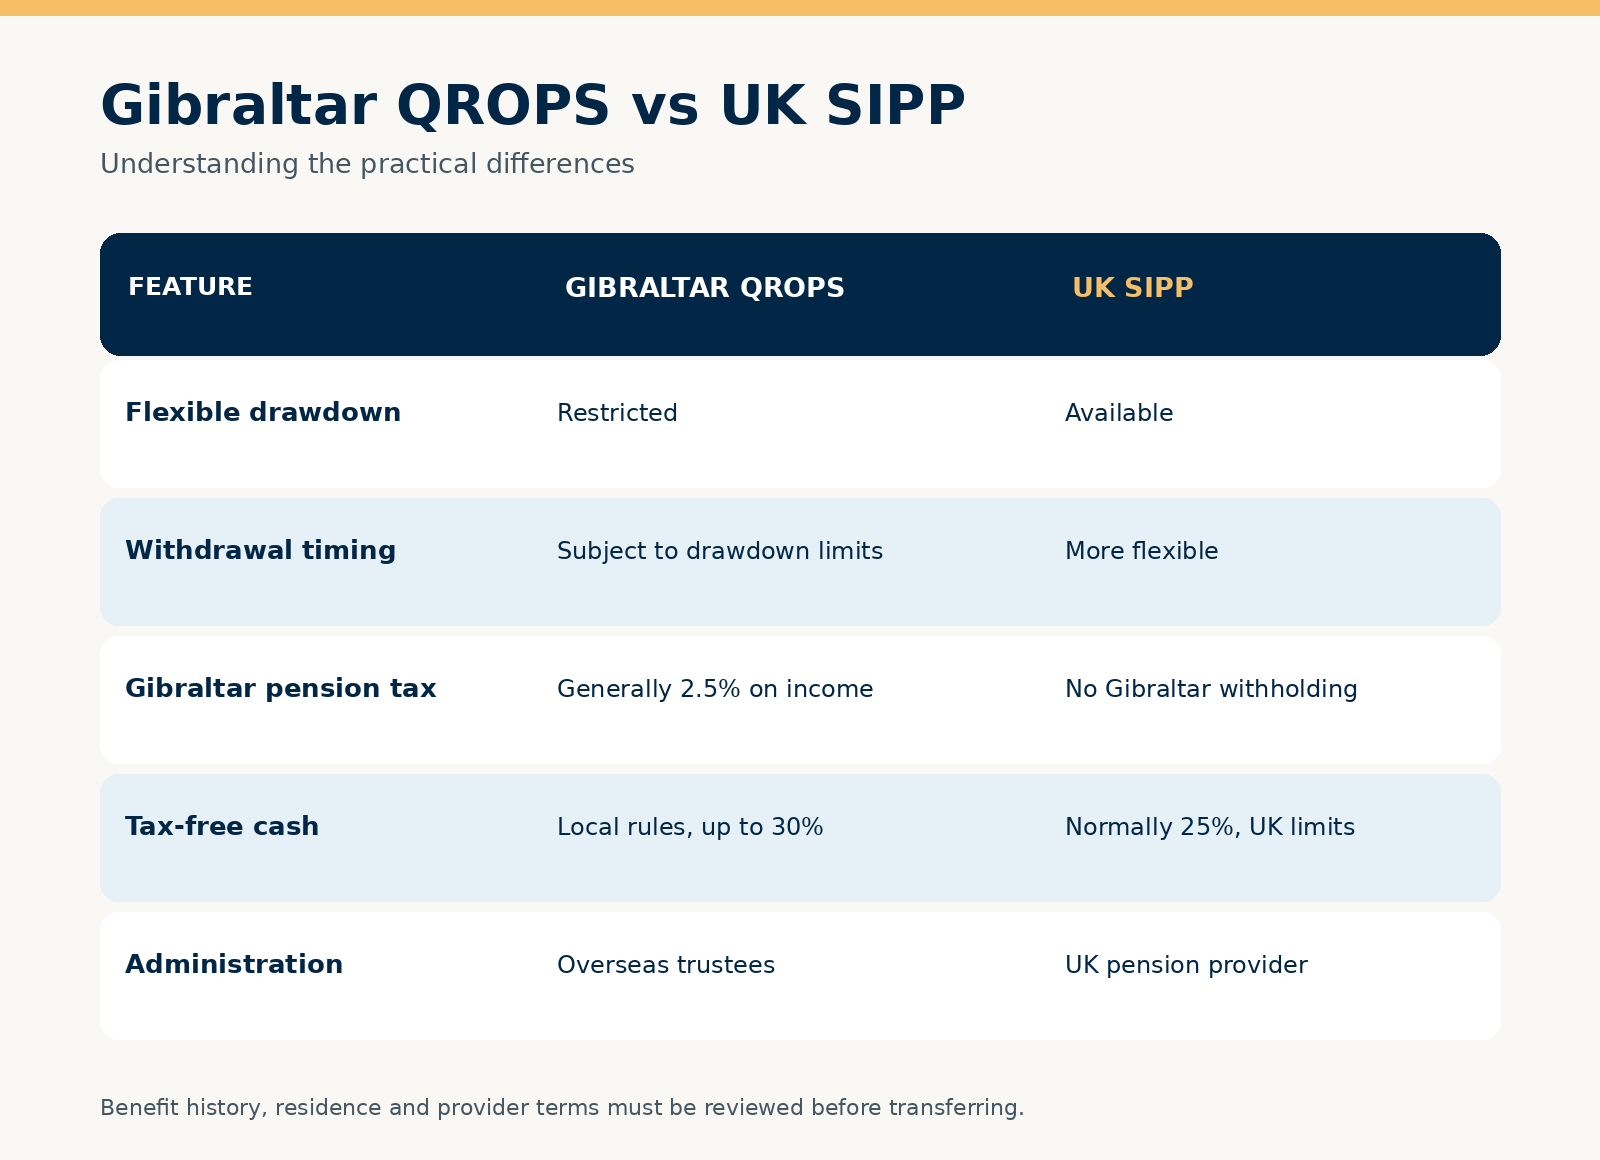
The ability to take flexible withdrawals can be particularly valuable when retirement income needs change over time.
However, transferring to a UK SIPP does not mean that any existing Gibraltar entitlement to a larger tax-free lump sum will automatically be preserved. The tax-free cash position must be reviewed before transferring, particularly where benefits have already been taken.
Can You Transfer a Gibraltar QROPS to a UK SIPP?
Yes. A Gibraltar QROPS can generally be transferred to a suitable UK registered pension scheme, provided that the transferring trustees and receiving provider are satisfied that the relevant requirements have been met.
A transfer to a UK registered pension scheme is not ordinarily subject to the 25% overseas transfer charge. That charge is principally concerned with qualifying transfers to overseas pension schemes, rather than transfers back into the UK.
This is an important distinction because the rules concerning transfers into a QROPS have become more restrictive.
However, other tax considerations, scheme restrictions and potential charges still need to be investigated.
In particular, the receiving UK pension provider must be willing to accept the overseas transfer and any associated pension benefit history.
Transferring From Momentum or Sovereign Gibraltar QROPS
Two established names associated with Gibraltar QROPS arrangements are Momentum Pensions and Sovereign.
Both have administered Gibraltar pension arrangements for internationally mobile individuals, including those with pension savings originally transferred from the UK.
I have been involved in helping clients arrange transfers out of Gibraltar QROPS arrangements, and one of the most important aspects is understanding the requirements of the existing trustees.
The process is not necessarily the same as a straightforward transfer between two UK pension providers.
The trustees may require additional documentation, confirmation of the receiving pension scheme, information about the member’s tax residence and evidence that the transfer can proceed without creating unintended tax consequences.
Why Gibraltar Trustees May Request Tax Advice
In some cases, Gibraltar QROPS trustees request tax advice or a written tax opinion before authorising a transfer to a UK pension arrangement.
This is not unusual in cross-border pension planning.
Trustees have responsibilities under their scheme rules and applicable legislation, and may want confirmation of the tax implications for the member before releasing the funds.
The precise requirements vary between trustees and individual circumstances.
This can become an obstacle if the member has identified a UK SIPP but has not arranged the supporting advice required by the Gibraltar provider.
I can help coordinate this aspect of the transfer, including arranging appropriate tax advice where the trustees request it.
The objective is to ensure that the transfer is both properly advised and administratively straightforward, rather than allowing it to become delayed by avoidable documentation issues.
How Does a Gibraltar QROPS to UK SIPP Transfer Work?
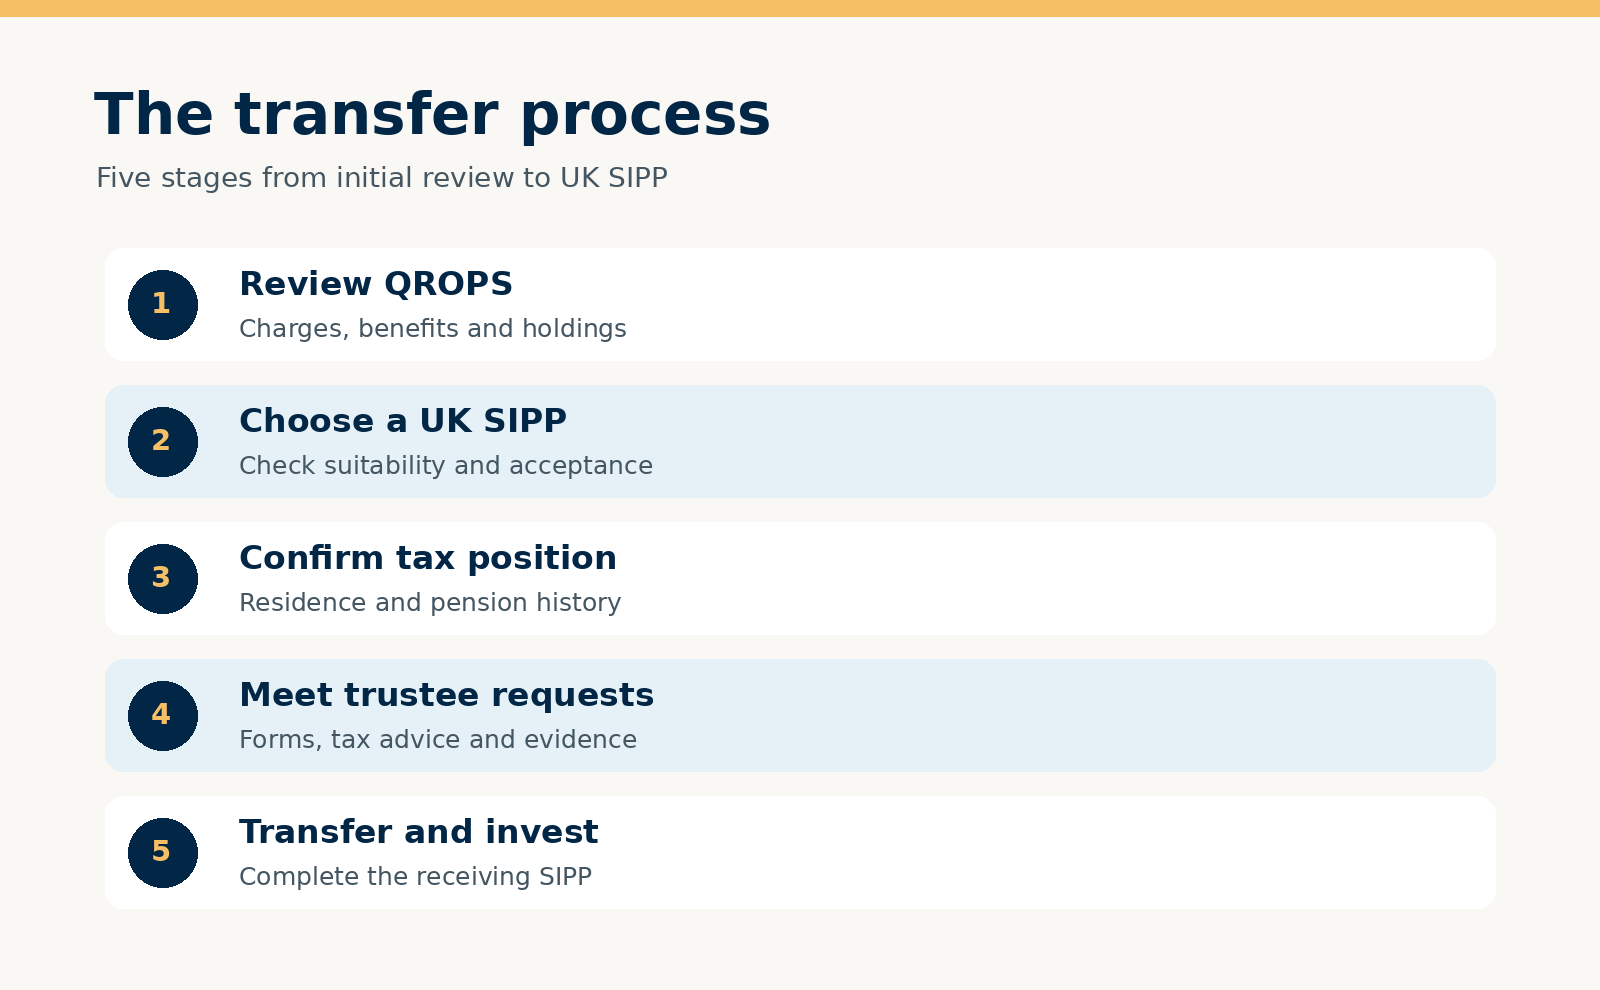
Although the requirements vary between pension providers, I would generally approach the transfer through the following stages.
Review the Existing Gibraltar QROPS
The starting point is to establish the current pension value, investment holdings, charges, withdrawal arrangements and any benefits already taken.
This includes checking whether there are exit charges, protected benefits or other features that could be lost following a transfer.
Assess Whether a UK SIPP Is Appropriate
A UK SIPP should be selected on the basis of suitability, investment flexibility, costs and the provider’s ability to accept the Gibraltar transfer.
For someone planning to retire in the UK, this will also involve reviewing the proposed pension alongside their other retirement assets and sources of income.
Confirm the Tax Position
Before proceeding, I would review the member’s tax residence, pension benefit history and any potential implications of moving the pension back to the UK.
Where specialist tax advice is required, this should be addressed before the transfer instruction is finalised.
Satisfy the Gibraltar Trustees’ Requirements
This can include transfer forms, identity verification, receiving-scheme confirmation, tax documentation and any additional declarations requested by the trustees.
Ensuring that the documentation is complete at the outset can help reduce delays.
Transfer and Reinvest the Pension
Once approved, the Gibraltar QROPS transfers the pension assets or proceeds to the receiving UK SIPP in accordance with the providers’ requirements.
The pension can then be invested in a portfolio aligned with the client’s objectives, investment horizon and retirement income requirements.
An Example: Returning to the UK With a Gibraltar QROPS
Consider someone who spent many years working overseas and transferred their pension into a Gibraltar QROPS.
They are now returning to the UK and have a pension worth £500,000.
They intend to retire gradually, drawing income as required while retaining sufficient investments for the longer term.
Under their Gibraltar pension arrangements, withdrawals are subject to the scheme’s applicable drawdown restrictions and Gibraltar’s 2.5% tax on taxable pension income.
By contrast, transferring to a suitable UK SIPP could allow them to use flexi-access drawdown.
They might decide to draw larger amounts in years when expenditure is higher, reduce withdrawals in other years, or coordinate pension income with their cash savings and other investments.
The benefit is not necessarily lower tax. In fact, taking substantial taxable withdrawals from a UK SIPP can increase an individual’s UK income tax liability.
The principal advantage is control: being able to structure withdrawals around the client’s financial circumstances rather than the restrictions imposed by the Gibraltar pension arrangement.
This is a hypothetical illustration, not a recommendation to transfer.
When Might Keeping Your Gibraltar QROPS Make More Sense?
Despite the potential advantages of returning a Gibraltar pension to the UK, a transfer will not always be appropriate.
For example, an individual who remains permanently resident outside the UK may have different tax considerations.
The existing Gibraltar scheme might also offer valuable benefits, a suitable investment arrangement or a favourable tax outcome in their country of residence.
Additionally, someone who has not yet accessed their pension should carefully consider the interaction between Gibraltar’s lump-sum rules and the UK tax-free cash allowances.
The right decision depends on where you live, how you intend to use the pension and what you want your retirement arrangements to achieve.
My Approach to Gibraltar QROPS Transfers
I am a Chartered Financial Planner and Chartered Investment Adviser, with more than 20 years’ experience advising internationally mobile individuals and families.
My work regularly involves UK and international pensions, including QROPS, SIPPs and the complexities that arise when clients move between countries.
I have direct experience of helping clients with transfers from Gibraltar QROPS arrangements, including navigating the requirements of Gibraltar trustees and coordinating the additional documentation necessary to complete a transfer.
However, I see the pension transfer as part of a wider financial planning exercise.
The important question is not simply whether your Gibraltar QROPS can be moved to the UK. It is whether doing so will leave you with a more suitable, flexible and sustainable retirement strategy.
That means considering the investments, pension charges, future withdrawals, tax position and the way the pension fits alongside your other assets.
Thinking About Transferring Your Gibraltar QROPS?
If you currently hold a Gibraltar QROPS with Momentum, Sovereign or another provider, and are considering moving it to a UK SIPP, I’d be delighted to have an initial conversation.
I can help you assess whether a transfer is appropriate, coordinate with the existing Gibraltar trustees and assist with obtaining any additional tax advice required to progress the transfer.
The aim is to give you clarity over your options and, where a transfer makes sense, help you move forward with confidence.
Technical references
Gibraltar Government — Imported Pension Scheme Guidance: drawdown limits, trustee discretion and pension taxation.
Gibraltar Finance Centre — QROPS: the 2.5% pension income tax and the conditional ability to take up to 30% as a retirement lump sum.
HMRC Pensions Tax Manual — PTM102300: confirms that transfers from QROPS to UK registered pension schemes are outside the overseas transfer charge.
HMRC — UK–Gibraltar Double Taxation Treaty Summary: useful for determining how Gibraltar pension income interacts with UK tax residence.
Frequently Asked Questions
Can I transfer my Gibraltar QROPS to a UK SIPP?
Yes. Gibraltar QROPS can generally be transferred to a UK registered pension scheme, including a suitable SIPP, provided the transferring trustees and receiving provider accept the transfer and their requirements are met. A transfer back to a UK registered pension is not ordinarily subject to the 25% overseas transfer charge.
Do Gibraltar QROPS allow flexi-access drawdown?
Gibraltar QROPS do not generally offer the same flexi-access drawdown arrangements available through UK SIPPs. Income withdrawals are ordinarily subject to drawdown restrictions designed to preserve retirement income. A UK SIPP offering flexi-access drawdown may provide substantially greater control over the timing and amount of withdrawals.
What tax applies to Gibraltar QROPS withdrawals?
Taxable pension income from Gibraltar QROPS is generally subject to Gibraltar income tax at 2.5%. Additional taxation may apply in the member's country of tax residence, including the UK. The availability of double taxation relief and the correct treatment of individual withdrawals should be established before benefits are taken.
Can I transfer a Momentum or Sovereign Gibraltar QROPS to the UK?
Transfers from Gibraltar QROPS arrangements administered by Momentum and Sovereign can generally be considered, subject to the terms of the scheme and acceptance by the receiving UK pension provider. The trustees may request additional documentation, including tax advice, before authorising the transfer.
Why might Gibraltar QROPS trustees ask for tax advice before a transfer?
Gibraltar trustees may request written tax advice or confirmation of the implications of transferring to a UK pension scheme. This helps them establish the member's circumstances and comply with their obligations. Russell Hammond can coordinate the transfer process and help arrange appropriate specialist tax advice where requested by the trustees.
Continue reading
Moving Back to the UK with a QROPS? Your Complete Guide
Returning to the UK after living overseas can raise a number of important financial planning questions, particularly if you hold pension benefits within a Qualifying Recognised Overseas Pension Scheme [...]
Momentum QROPS: A Guide to Your Pension, Changing Adviser and Retirement Planning
If you hold a Qualifying Recognised Overseas Pension Scheme (QROPS) with Momentum Pensions, you may have established your pension many years ago, perhaps while living and working overseas. Since [...]
Financial Advice for British Expats in Oman: Pension Planning, Investment Strategy & IHT Mitigation
How to Protect and Grow Your Wealth While Living in Oman For British expats living in Oman, the combination of tax-free income, a relaxed lifestyle, and strong earning potential [...]