Moving Back to the UK with a QROPS? Your Complete Guide
Key takeaways
- You can transfer a QROPS back to the UK – An existing QROPS can generally be transferred into a UK registered pension scheme, including a SIPP, provided the relevant conditions are met.
- The 25% overseas transfer charge does not apply – Transferring an existing QROPS into a UK registered pension is outside the scope of the overseas transfer charge, although other tax considerations may remain.
- There is no general five-year waiting requirement – You do not ordinarily have to wait five years before transferring a QROPS back to the UK, although the history of your original pension transfer should be reviewed.
- A UK SIPP may offer lower costs and greater flexibility – Transferring can simplify retirement planning and potentially reduce charges, but existing benefits, investment options and any transfer penalties must be considered.
- Previously accessed pension benefits require particular care – Transferring a QROPS does not automatically restore tax-free cash entitlements, and existing crystallised benefits may need to retain their status within the receiving UK pension.
Returning to the UK after living overseas can raise a number of important financial planning questions, particularly if you hold pension benefits within a Qualifying Recognised Overseas Pension Scheme (QROPS).
Perhaps you transferred your UK pension into a QROPS while living abroad. Alternatively, you may have accumulated pension benefits through an overseas employer and subsequently transferred them into an international pension arrangement.
Whatever your circumstances, returning to Britain raises an important question: should you retain your existing QROPS, or would transferring it back into a UK pension, such as a Self-Invested Personal Pension (SIPP), be more appropriate?
The good news is that transferring a QROPS back to the UK is often possible, and doing so does not, in itself, trigger the 25% overseas transfer charge.
However, there are important considerations, including the treatment of existing pension benefits, tax-free cash entitlements, investment costs and the suitability of the receiving UK pension arrangement.
In this guide, I’ll explain how QROPS transfers back to the UK work, the potential benefits and drawbacks, and what you should consider before making a decision.
Can I Transfer My QROPS Back to the UK?
Yes. HMRC permits pension funds held within a QROPS to be transferred back into a UK registered pension scheme, including a SIPP, subject to the relevant transfer conditions being satisfied.
HMRC specifically confirms this in its Pensions Tax Manual, section PTM103500.
Importantly, a transfer from a QROPS into a UK registered pension is not treated as making a new pension contribution. Instead, it represents the transfer of existing pension rights from one arrangement to another.
For someone who previously established a QROPS while living abroad and has subsequently returned to the UK, a transfer can provide an opportunity to simplify their retirement planning.
A UK SIPP may offer several potential advantages:
- Access to a broad range of investments, including low-cost, diversified investment funds.
- Flexible retirement income options, subject to the nature of your existing pension benefits.
- Potentially lower ongoing pension administration and investment costs.
- Consolidation alongside existing UK pension arrangements.
- Easier coordination of pension withdrawals with other UK income and investments.
- Access to relevant UK regulatory protections where eligibility conditions are met.
However, returning to the UK does not mean that you are required to transfer your QROPS into a UK pension. Indeed, I continue to advise and manage QROPS arrangements for many clients who have subsequently returned to the UK, where retaining their existing overseas pension remains appropriate for their individual circumstances and financial objectives.
Thus, you can generally continue to hold a QROPS while living in the UK, subject to the terms of your particular scheme.
The important question is whether your existing arrangement continues to meet your financial objectives and provides the appropriate combination of investment choice, flexibility, tax treatment and overall costs.
Will I Pay 25% Tax When Transferring My QROPS Back to the UK?
This is understandably one of the biggest concerns for people considering transferring their QROPS.
The 25% overseas transfer charge was introduced in March 2017 and can apply to certain transfers from UK registered pension schemes into QROPS, as well as some subsequent transfers between overseas pension arrangements.
However, there is an important distinction between transferring a UK pension out to a QROPS and transferring an existing QROPS back into a UK registered pension.
A transfer from a QROPS into a UK registered pension scheme is outside the scope of the 25% overseas transfer charge.
This is explicitly confirmed by HMRC in its Pensions Tax Manual, section PTM102300.
An example: Transferring a Malta QROPS back to the UK
Consider someone who previously lived in Dubai and transferred their UK pension into a Momentum Maltese QROPS.
Several years later, they return to the UK and decide that consolidating their pension benefits into a UK SIPP would be more appropriate.
Provided the transfer satisfies the relevant requirements, transferring the Maltese QROPS into a UK registered SIPP would not, in itself, trigger the 25% overseas transfer charge.
This is an important distinction because the tax treatment of transferring a pension back into the UK differs from transferring a UK pension overseas.
Nevertheless, the absence of an overseas transfer charge does not mean every aspect of the transaction is free from tax considerations.
The original transfer history, any benefits previously accessed and the tax treatment of future withdrawals should still be reviewed carefully.
Do I Have to Wait Five Years Before Transferring My QROPS Back?
There is considerable confusion surrounding the five-year rules applicable to overseas pension arrangements.
This is partly because several different rules apply to QROPS, including the overseas transfer charge relevant period and separate provisions concerning pension payments and reporting obligations.
There is no general requirement to wait five years before transferring an existing QROPS into a UK registered pension scheme.
The overseas transfer charge relevant period can be important where an individual transfers a UK pension to a QROPS and subsequently experiences a change in circumstances, such as moving to another country.
However, that does not create a blanket five-year restriction on transferring an existing QROPS back into the UK.
There is also a technical distinction between the overseas transfer charge relevant period and the rules applying to payments from overseas pension schemes to certain members with UK tax-relieved pension funds.
For these reasons, I would review the original pension transfer date, your residence history, the source of the pension benefits and whether any withdrawals have already been made.
The fact that a transfer back to the UK is permitted does not remove the need to understand the history of the underlying pension funds.
Should I Keep My QROPS or Transfer It to a UK SIPP?
There is no universally correct answer.
In some circumstances, retaining a QROPS may be entirely appropriate. In others, transferring into a UK SIPP may offer a simpler, more flexible or lower-cost solution.
The following comparison highlights some of the important considerations.
| Consideration | Existing QROPS | UK SIPP |
|---|---|---|
| Investment options | Depend on the overseas provider and scheme structure | Often broad investment choice, including funds and ETFs |
| Administration fees | May include overseas trustee and platform charges | UK provider charges, potentially with a simpler fee structure |
| Retirement income | Subject to scheme rules and applicable tax legislation | UK drawdown options, subject to existing benefit status |
| Consolidation | May require coordination with overseas trustees | Can potentially consolidate alongside other UK pensions |
| Regulation | Overseas regulatory framework | UK regulatory framework, with protection dependent on eligibility |
| Death benefits | Depend on scheme rules and tax legislation | UK pension death benefit rules |
| Suitability | Depends on individual circumstances | Depends on individual circumstances |
There are several factors I would consider particularly important.
1. Overall pension charges
Some QROPS arrangements contain multiple layers of charges, including overseas trustee fees, platform administration charges, investment management costs and financial adviser fees.
Depending on the provider, these charges can make the pension relatively expensive to maintain.
By contrast, a UK SIPP may offer a more straightforward charging structure, particularly where the pension can be invested in low-cost diversified funds.
However, not every QROPS is expensive, and not every UK SIPP is inexpensive.
The important consideration is the total cost of the existing arrangement compared with a suitable alternative.
2. Investment strategy
The investment strategy held within your pension will be a major influence on your long-term retirement outcomes.
Whether you retain a QROPS or transfer into a UK SIPP, I believe the emphasis should be on establishing an appropriate asset allocation, diversifying investments and controlling unnecessary costs.
For example, someone who has recently retired and intends to draw an income from their pension may require a different investment strategy from someone who is still working and has another 20 years until retirement.
The investment portfolio should therefore be designed around your financial objectives, attitude to investment risk and capacity for loss.
3. Retirement income flexibility
For those intending to retire in the UK, the ability to coordinate pension withdrawals alongside other income and investments can be particularly valuable.
A UK SIPP may offer greater flexibility through flexi-access drawdown, particularly when compared with certain overseas pension arrangements, such as Gibraltar QROPS that do not ordinarily offer this facility. This can allow pension withdrawals to be coordinated more effectively with State Pension income, other occupational pensions, ISAs, cash savings and investments, helping to create a more flexible and potentially tax-efficient retirement income strategy.
However, the precise options available will depend on the nature of the pension benefits transferred and whether any have already been accessed.
4. Future residence plans
If you intend to remain in the UK permanently, consolidating suitable pension arrangements into a UK registered pension may make sense.
Conversely, if you expect to relocate overseas again, retaining an international pension arrangement may deserve consideration.
Your future country of residence, applicable tax treaties and expected retirement income requirements should all form part of the assessment.
What Happens to My Tax-Free Cash When I Transfer?
This is one of the most important technical considerations when transferring a QROPS back into the UK.
Where pension benefits remain uncrystallised, it will normally be possible to access a pension commencement lump sum following a transfer into a UK registered pension, subject to the relevant rules and your available lump sum allowances.
However, where benefits have already been crystallised or pension withdrawals commenced within the QROPS, the position can be more complicated.
Transferring a QROPS into a UK SIPP does not automatically restore any tax-free cash entitlement previously used.
For example, if you have already designated pension funds into drawdown, the receiving UK pension may need to preserve the existing pension benefit status.
HMRC specifically provides that where drawdown pension rights are transferred from a QROPS into a UK registered scheme under the relevant provisions, the replacement drawdown arrangement is treated as a continuation of the original pension for specified tax purposes.
Consequently, a new pension commencement lump sum cannot simply be taken from those transferred drawdown rights.
Before arranging a transfer, I would therefore want to establish:
- Whether your QROPS contains crystallised or uncrystallised funds.
- Whether tax-free cash has previously been taken.
- Whether any pension benefits are already in drawdown.
- Whether any protected pension rights or lump sum entitlements exist.
- Whether the proposed UK pension provider can accept and correctly administer those benefits.
These considerations are particularly important for individuals with larger pension arrangements or more complicated pension transfer histories.
Can I Transfer a Malta QROPS to a UK SIPP?
Malta has historically been a popular jurisdiction for UK expatriates holding overseas pension arrangements, with Momentum and Sovereign being the two main trustees operating Maltese schemes.
Many individuals who previously worked in the Middle East, Asia or elsewhere hold pensions within Maltese QROPS arrangements.
If you have returned to the UK with a Maltese QROPS, transferring the arrangement into a UK registered SIPP is normally possible.
However, the transfer will depend on the rules of the particular Maltese pension scheme and the requirements of the proposed receiving provider.
Factors that may need to be considered include:
- The scheme’s rules concerning outgoing transfers.
- The source and nature of the underlying pension benefits.
- Whether benefits have already been crystallised.
- Any surrender penalties or transfer administration fees.
- Whether existing investments can be transferred or must first be sold.
- The receiving UK pension provider’s acceptance requirements.
It is also important to recognise that not every UK SIPP provider is willing to accept transfers from overseas pension schemes.
Some providers may accept QROPS transfers subject to additional documentation, while others may decline them altogether.
Establishing the receiving provider’s requirements at the outset can help avoid unnecessary delays and administrative complications.
What If My QROPS Originally Came from a Non-UK Pension?
This is a particularly important consideration for internationally mobile individuals.
Not every QROPS contains exclusively UK pension benefits.
For example, someone may have accumulated retirement savings through an overseas occupational pension scheme while working for a multinational employer such as Shell.
Those benefits may subsequently have been transferred into a Maltese QROPS, either independently or alongside pension funds originally accumulated in the UK.
Consequently, a single QROPS arrangement can potentially contain pension benefits with different origins and tax histories.
The fact that pension funds are now held within a QROPS does not necessarily mean that every UK SIPP provider will accept them or that all benefits will receive identical tax treatment.
The original source of the funds, whether UK tax relief was previously obtained and the nature of the benefits can all be relevant.
For example, pension benefits originating from an overseas employer’s pension scheme may need to be considered differently from benefits originally accumulated within a UK registered pension.
Before recommending a transfer, I would therefore review the underlying pension history and establish the requirements of the proposed receiving UK pension arrangement.
This is precisely the sort of situation where experience with international pension structures can be valuable.
How Does Returning to the UK Affect My Tax Residence?
Before considering any significant changes to overseas pension arrangements, it is important to establish your UK tax residence position.
The UK Residence Decision Tree can help you explore whether you are likely to be UK tax resident under the Statutory Residence Test.
The test considers factors including the number of days spent in the UK, overseas and UK working patterns, accommodation and family connections.
For someone returning to the UK, the precise date on which UK tax residence begins can have important implications for investment income, pension withdrawals and other financial planning decisions.
In some circumstances, split-year treatment may apply, meaning the tax year can be divided into a UK part and an overseas part.
However, split-year treatment is not automatic simply because someone moves back to the UK.
Understanding your residence status before making significant pension withdrawals or investment decisions is therefore an important part of the planning process.
Could the Foreign Income and Gains Regime Be Relevant?
From 6 April 2025, the UK introduced a new four-year Foreign Income and Gains regime for qualifying individuals becoming UK tax resident after at least 10 consecutive tax years of non-UK residence.
The FIG regime can offer valuable planning opportunities for eligible returning expatriates, particularly where they have significant overseas investments or income-producing assets.
However, it is important not to assume that all overseas pension income will qualify for relief.
Certain pension payments, including payments to relevant members of overseas pension schemes that fall within the UK member payment provisions, are specifically excluded from FIG relief.
The treatment of a particular overseas pension payment therefore requires careful consideration of the nature of the benefits and the applicable tax legislation.
For someone returning to the UK with a QROPS alongside other overseas investments, the wider financial planning implications may extend well beyond the pension transfer itself.
What About Inheritance Tax and Pension Death Benefits?
Inheritance tax is becoming an increasingly important consideration when reviewing pension arrangements.
The UK government has legislated to bring most unused pension funds and pension death benefits within the scope of inheritance tax for deaths occurring on or after 6 April 2027.
These reforms may have significant implications for individuals holding substantial pension assets.
In particular, retaining a pension overseas should not automatically be assumed to provide an inheritance tax advantage over holding a UK registered pension.
The position depends on the nature of the pension scheme, the individual’s inheritance tax residence status and the applicable legislation.
For internationally mobile individuals, the UK’s long-term residence rules are also relevant to determining the extent to which worldwide assets may fall within the scope of UK inheritance tax.
It is also important to distinguish inheritance tax treatment from the separate income tax rules governing pension death benefits.
For someone returning to the UK with a substantial QROPS, I would therefore assess the pension in the context of their wider estate and succession planning, rather than viewing the transfer as an isolated transaction.
How Much Could Transferring Your QROPS Save?
Pension charges can vary considerably between overseas pension arrangements and UK SIPPs. The following hypothetical example illustrates how reducing ongoing charges could affect a £500,000 pension.
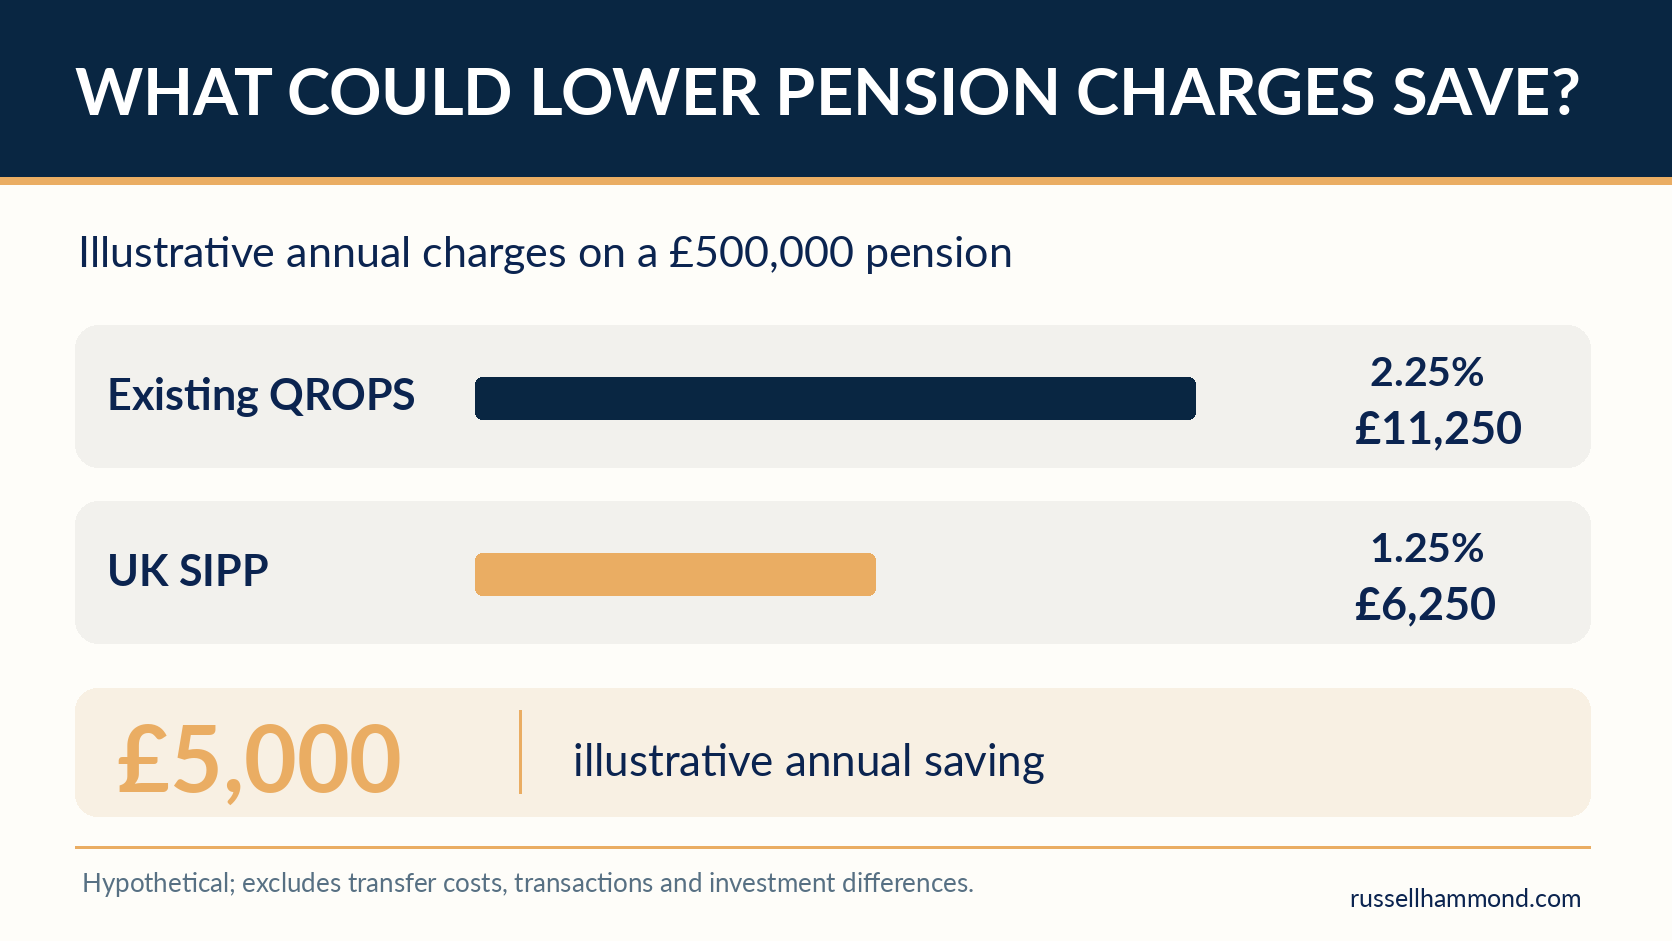
Although lower charges can improve long-term retirement outcomes, cost savings alone do not justify transferring a pension. Any recommendation must also consider existing guarantees, pension benefits, investment suitability, tax treatment and your wider financial circumstances.
How Do I Transfer My QROPS Back to the UK?
Although individual providers have different requirements, the process will generally involve five stages.
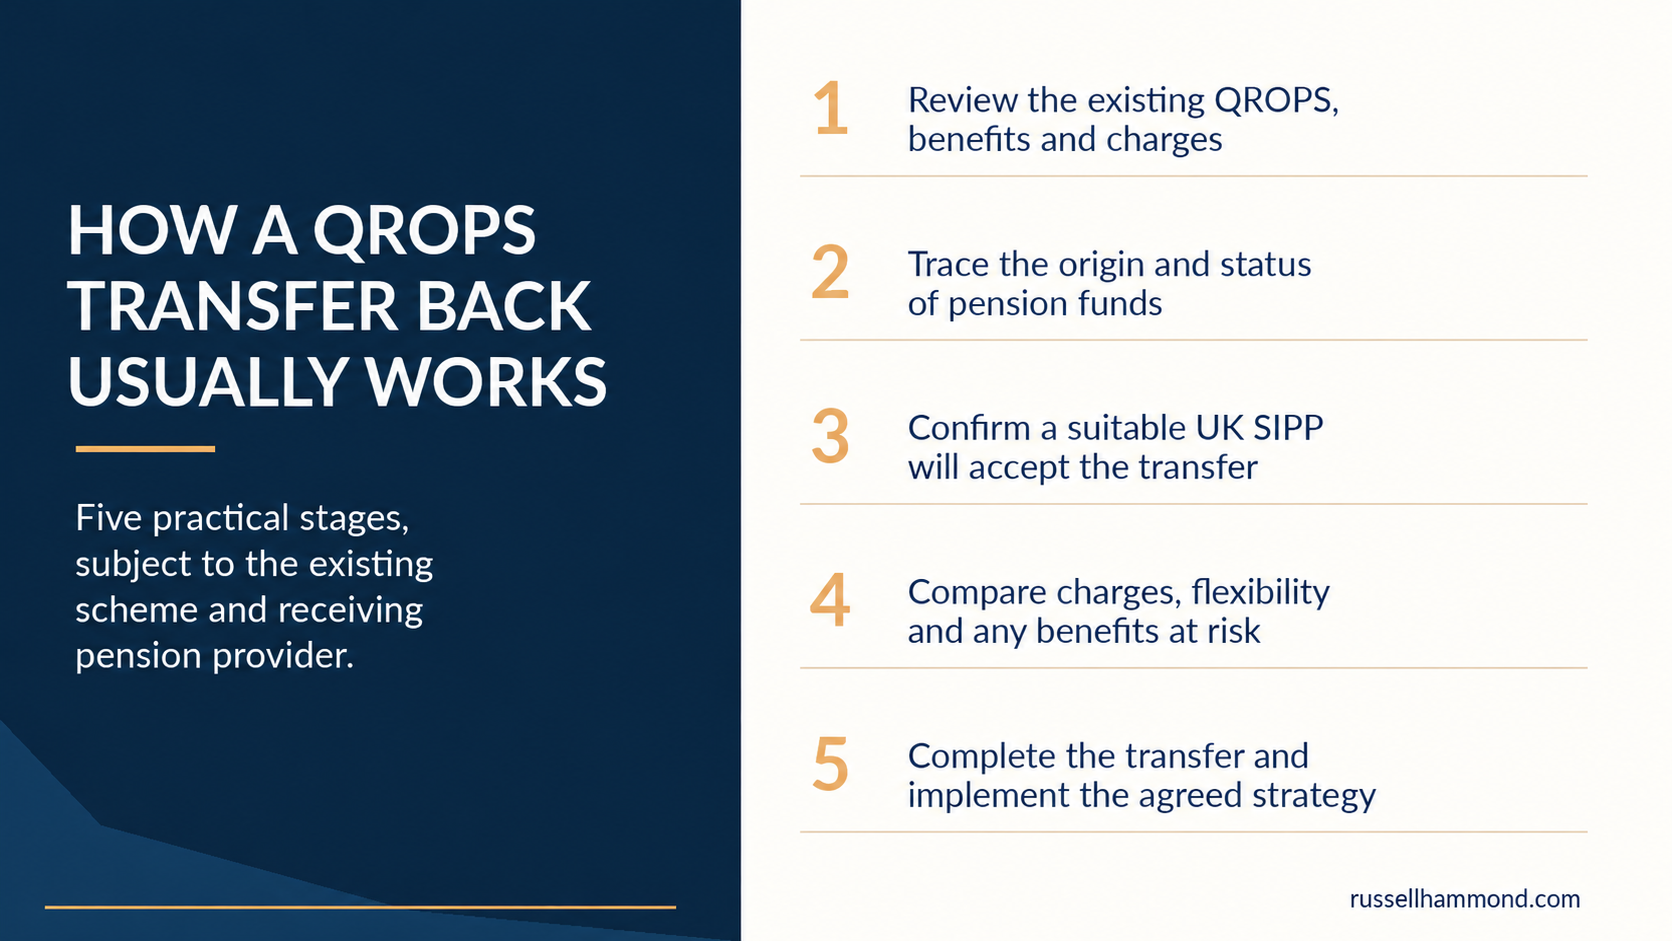
Step 1: Review the existing QROPS
Obtain a current valuation, charging schedule, investment holdings and details of any pension benefits already taken.
This will help identify potential transfer restrictions, exit penalties or other matters requiring attention.
Step 2: Establish the pension’s history
Determine the original source of the pension funds, dates of previous transfers and whether benefits have been crystallised or withdrawn.
Understanding this history is particularly important where the QROPS contains both UK-derived and overseas pension benefits.
Step 3: Identify a suitable UK pension provider
Establish whether a prospective UK SIPP provider is willing to accept the transfer and can correctly administer the particular pension rights involved.
Not every UK pension provider accepts QROPS transfers.
Step 4: Compare the existing and proposed arrangements
Assess the overall costs, investment options, retirement income flexibility, death benefits, tax considerations and potential loss of valuable existing rights.
The aim should be to establish whether the proposed transfer is genuinely beneficial in the context of your overall financial circumstances.
Step 5: Complete the transfer and implement your investment strategy
Once the appropriate checks and advice process have been completed, the overseas and UK pension providers can coordinate the transfer.
Following completion, the pension investments can be aligned with an agreed investment strategy and incorporated into your wider retirement income planning.
The time required will depend on the complexity of the arrangement, the providers involved and the documentation needed to complete the process.
How I Can Help
I am a UK-based Chartered Financial Planner and Chartered Investment Adviser, with more than 20 years of experience advising internationally mobile individuals and families.
Having spent many years working with British expatriates and overseas pension arrangements, I understand that returning to the UK involves more than simply transferring investments and pensions from one jurisdiction to another.
Your pension planning should be considered alongside your tax residence, investment strategy, retirement income requirements and wider financial objectives.
My approach focuses on evidence-based investing, diversification, transparent investment costs and developing long-term relationships with clients.
Where appropriate, I can help you review your existing QROPS, assess the suitability of transferring into a UK SIPP and establish an investment and retirement income strategy consistent with your longer-term objectives.
If you’re planning to return to the UK, or have already returned and still hold a QROPS, please feel free to get in touch for an initial discussion about your circumstances and the options available to you.
Technical references
The following HMRC publications provide further information about the issues discussed in this article:
- HMRC PTM103500 — Transfers from QROPS to UK registered pension schemes
- HMRC PTM102300 — When the overseas transfer charge does not apply
- HMRC PTM102200 — Overseas transfer charge principles
- HMRC RFIG45200 — Disqualified income under the FIG regime
- HMRC — Inheritance tax on pensions: technical note
Important information: This article is intended for general information and does not constitute personal financial, investment or tax advice. Pension transfers can involve significant risks, including the potential loss of existing guarantees and benefits. Tax treatment depends on individual circumstances and may change. The value of investments can fall as well as rise, and you may receive back less than you invested.
Frequently Asked Questions
Can I keep my QROPS if I move back to the UK?
Yes. Returning to the UK does not automatically require you to transfer your QROPS into a UK pension. Many UK residents continue to hold overseas pension arrangements. However, it's sensible to review the costs, investment options, retirement benefits and tax implications to establish whether retaining the QROPS remains appropriate.
Is transferring a QROPS back to the UK tax-free?
A transfer from a QROPS into a UK registered pension scheme is outside the scope of the 25% overseas transfer charge. However, this does not necessarily mean every aspect of the transaction is free from tax considerations. The pension's transfer history, existing benefits and the tax treatment of future withdrawals should still be reviewed.
Can I transfer my QROPS to a UK SIPP?
Yes. HMRC permits transfers from QROPS arrangements into UK registered pension schemes, including SIPPs, subject to the relevant requirements. However, not all SIPP providers accept transfers from overseas pensions, particularly where existing benefits have been crystallised or the pension contains funds originally accumulated outside the UK.
Do I have to wait five years before transferring my QROPS back to the UK?
No. There is no general five-year waiting requirement preventing a QROPS from being transferred into a UK registered pension scheme. However, the original transfer history, overseas transfer charge rules and any continuing tax or reporting obligations should be considered before proceeding.
Can I transfer my QROPS if I have already taken tax-free cash?
Yes, you can. However, pension benefits that have already been crystallised or designated to drawdown may need to retain their existing status following the transfer. Transferring into a UK SIPP does not automatically create a new entitlement to tax-free cash from benefits that have already been accessed.
Can I transfer a Malta, Gibraltar or Isle of Man QROPS back to the UK?
Yes. QROPS arrangements established in Malta, Gibraltar and the Isle of Man may be transferred into a UK registered pension scheme, provided the relevant conditions are met. The transferring scheme's rules, existing pension benefits and the willingness of the UK provider to accept the transfer must all be considered.
Does transferring a QROPS count towards my pension annual allowance?
A transfer of existing QROPS pension rights into a UK registered pension scheme is not itself a new pension contribution and does not ordinarily use your annual allowance. However, any separate contributions or pension input arising alongside the transfer should be assessed under the applicable pension tax rules.
Will withdrawals from my QROPS be taxable after returning to the UK?
UK residents can be liable to UK income tax on withdrawals from overseas pension schemes, including QROPS. The treatment depends on the type of pension payment, the origin of the benefits and any applicable double taxation agreement. It's important to establish the tax position before making substantial withdrawals.
Are QROPS more expensive than UK SIPPs?
Not necessarily, although some QROPS arrangements carry additional trustee, administration and investment charges. A UK SIPP may offer a simpler or lower-cost alternative. Any comparison should consider total ongoing charges, one-off transfer costs, investment suitability and the benefits or flexibility that could be lost by transferring.
Should I transfer my QROPS before or after returning to the UK?
There is no universally preferable time to transfer a QROPS. The appropriate timing depends on your tax residence, the history of the pension, the benefits already taken and the requirements of the receiving provider. Ideally, the decision should be considered as part of your wider financial planning before returning to the UK.
Continue reading
Utmost International Offshore Bond: What to Know Before You Invest
Why You Shouldn’t Rush Into an Offshore Bond Without Reading the Fine Print If you’re reading this, you’ve likely been recommended an offshore international investment bond — perhaps from [...]
Momentum QROPS: A Guide to Your Pension, Changing Adviser and Retirement Planning
If you hold a Qualifying Recognised Overseas Pension Scheme (QROPS) with Momentum Pensions, you may have established your pension many years ago, perhaps while living and working overseas. Since [...]
Transfer a Gibraltar QROPS to a UK SIPP: Rules, Tax and Drawdown
If you have a pension held in a Gibraltar Qualifying Recognised Overseas Pension Scheme (QROPS), you may be surprised to discover that the rules governing withdrawals are quite different [...]