Momentum QROPS: A Guide to Your Pension, Changing Adviser and Retirement Planning
Key takeaways
- Established provider: Momentum has a longstanding presence in the QROPS market, with its Malta Retirement Trust established in 2011.
- Changing adviser: Existing Momentum QROPS members can appoint a new financial adviser, subject to the relevant requirements, without necessarily transferring their pension.
- Returning to the UK: Moving back to the UK does not automatically require a QROPS to be transferred into a UK SIPP.
- Retirement withdrawals: Lump sums and pension income require careful consideration of the scheme rules, the origin of the pension funds and the member’s tax residence.
- Experienced advice: I have worked with Momentum arrangements over many years and can help existing members review their investment and retirement strategies.
If you hold a Qualifying Recognised Overseas Pension Scheme (QROPS) with Momentum Pensions, you may have established your pension many years ago, perhaps while living and working overseas.
Since then, your circumstances may have changed. You might have returned to the UK, moved to another country, approached retirement or simply lost contact with the financial adviser who originally arranged your pension.
The good news is that changing your financial adviser does not necessarily mean changing your pension provider.
Momentum has been involved in the international pension market for many years, providing QROPS arrangements across several established jurisdictions. Having worked with Momentum and its pension solutions over many years myself, I am familiar with its approach to pension administration, investment arrangements and retirement benefits.
In this article, I explain the history of QROPS, Momentum’s place in the international pensions market, and the considerations for existing members who need financial advice or are considering changing adviser.
The history of QROPS: nearly two decades of international pension planning
QROPS were introduced as part of the substantial changes to UK pension legislation on 6 April 2006, commonly referred to as A-Day.
The new framework made it possible for qualifying overseas pension schemes to receive transfers from UK registered pensions, subject to HM Revenue & Customs requirements.
For British expatriates and internationally mobile individuals, this created new opportunities to manage retirement savings across international borders.
During the years that followed, QROPS became an established feature of international retirement planning. Jurisdictions including Malta, Gibraltar and the Isle of Man developed pension arrangements designed to accommodate individuals with UK pension benefits and international circumstances.
However, the QROPS market has evolved considerably since those early years.
In March 2017, the UK introduced the Overseas Transfer Charge, potentially imposing a 25% charge on certain transfers to overseas pension schemes.
Further changes followed, including the introduction of the Overseas Transfer Allowance in April 2024 and restrictions on transfer-charge exemptions for schemes in the European Economic Area and Gibraltar from October 2024.
These developments underline an important distinction: the rules governing a new transfer to a QROPS are not necessarily the same as those governing an existing QROPS member’s pension.
For individuals who already hold a QROPS, the central questions are often less about establishing a new overseas pension and more about managing their existing retirement savings effectively.
Momentum Pensions: an established international pension provider
Momentum Pensions has a longstanding presence in the international pension market.
One example of this history is the Momentum Malta Retirement Trust, established in March 2011.
Today, Momentum offers QROPS solutions through Malta, Gibraltar and the Isle of Man, with arrangements administered under the relevant local regulatory frameworks.
Momentum Pensions Malta Limited is licensed as a Retirement Scheme Administrator by the Malta Financial Services Authority. Its Gibraltar pension operation is regulated by the Gibraltar Financial Services Commission, while its Isle of Man pension administration business is registered with the Isle of Man Financial Services Authority.
Momentum’s role as pension trustee or administrator is distinct from that of the financial adviser responsible for providing personal investment and retirement planning advice.
This distinction is particularly important for existing members.
Your pension provider may continue to administer your QROPS effectively, even if you would benefit from reviewing your investments, changing your adviser or revisiting your retirement income strategy.
My experience working with Momentum Pensions
I have worked in international financial planning for more than 20 years and have extensive experience advising clients with overseas pension arrangements.
Throughout my career, I have worked with Momentum and its QROPS solutions, helping clients navigate the complexities of pension investments, international retirement planning and the eventual withdrawal of retirement benefits.
My experience has given me an appreciation of the importance of having an experienced pension administrator, particularly when dealing with more complicated international arrangements.
Momentum’s established presence in the QROPS market, its technical knowledge and its familiarity with cross-border pension administration are important considerations.
I have also found that the most effective outcomes arise when the pension administrator and the financial adviser perform complementary roles.
Momentum provides the pension structure and administration. My role is to consider the client’s wider financial circumstances, recommend a suitable investment strategy, assess retirement income requirements and ensure their pension remains aligned with their long-term objectives.
I do not regard changing pension providers as a necessary consequence of changing financial advisers.
Indeed, where an existing Momentum arrangement remains suitable, retaining it may often be the most sensible approach.
Can you change the financial adviser on your Momentum QROPS?
Yes. Momentum has procedures allowing members to appoint a different financial adviser, subject to the relevant authorisation, documentation and acceptance requirements.
This can be particularly useful if your original adviser is no longer active, has moved to another business, no longer provides ongoing advice or cannot advise you in your current country of residence.
It may also be appropriate if you would simply prefer to work with an adviser offering a different approach to investment management and retirement planning.
Importantly, appointing a new adviser does not ordinarily require the pension to be transferred to another QROPS provider.
The existing Momentum pension can potentially remain in place while the appointed adviser reviews the arrangements and recommends appropriate changes.
Any changes to underlying investments or investment platforms would need to satisfy Momentum’s requirements and the terms of the relevant pension arrangement.
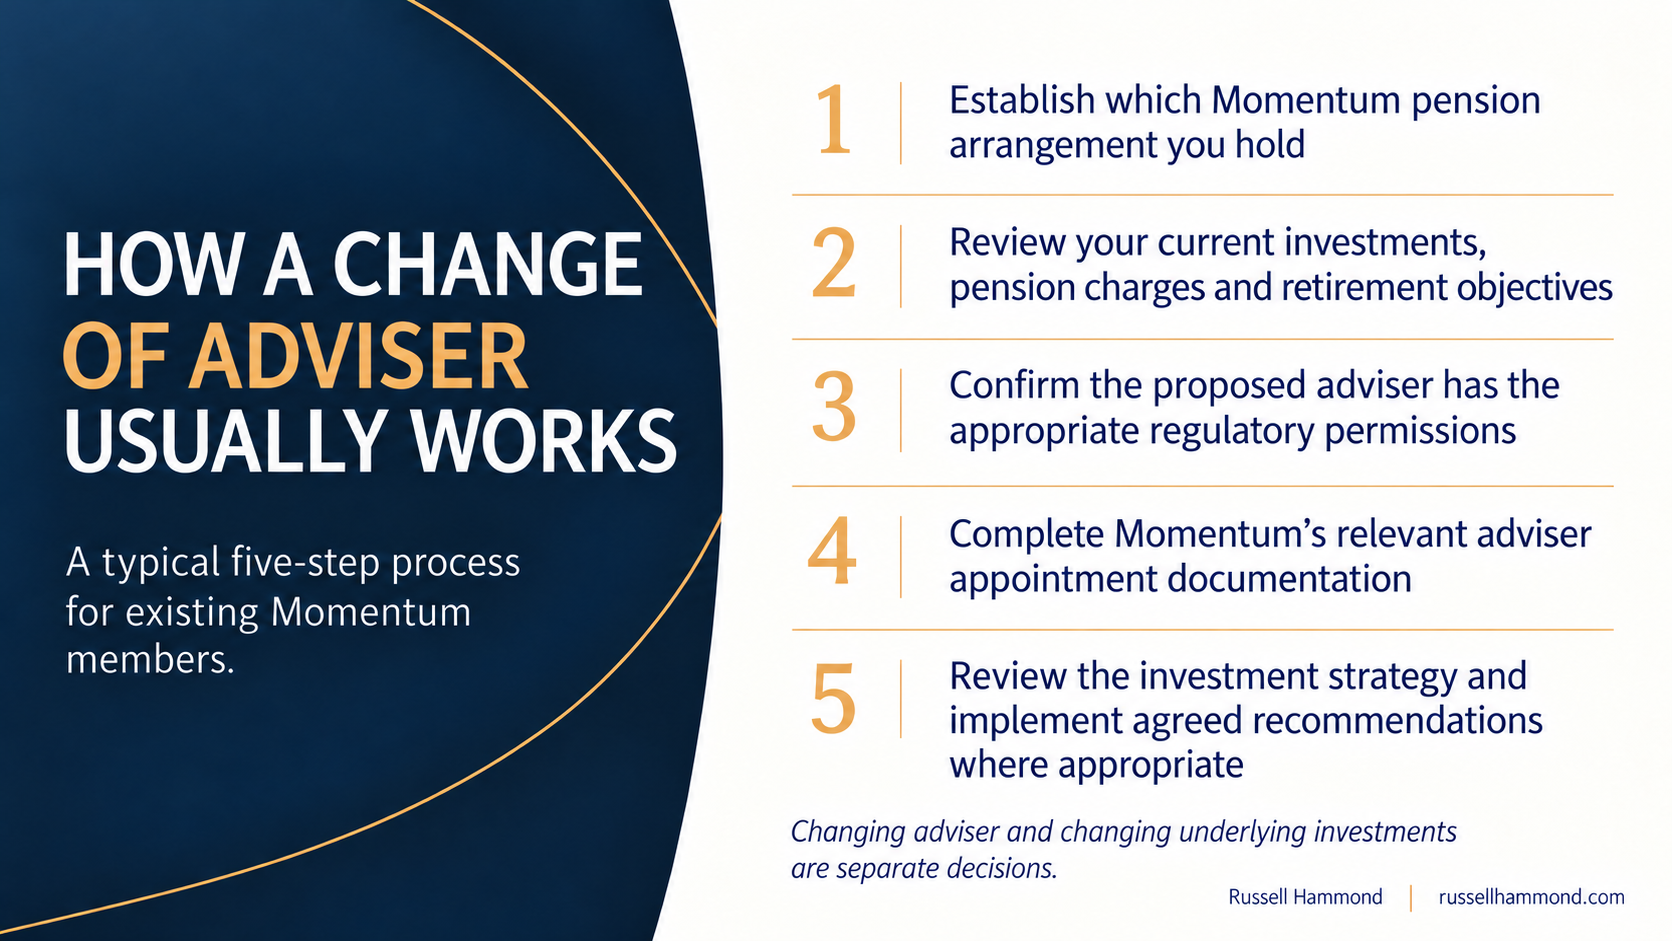
How does the change-of-adviser process work?
The precise process depends on the Momentum scheme and the member’s circumstances, but it will generally involve:
A change of adviser should also involve a clear explanation of any new advice fees, ongoing service arrangements and potential changes to the overall cost of your pension.
Changing the adviser and changing the underlying investments are separate decisions. One does not automatically require the other.
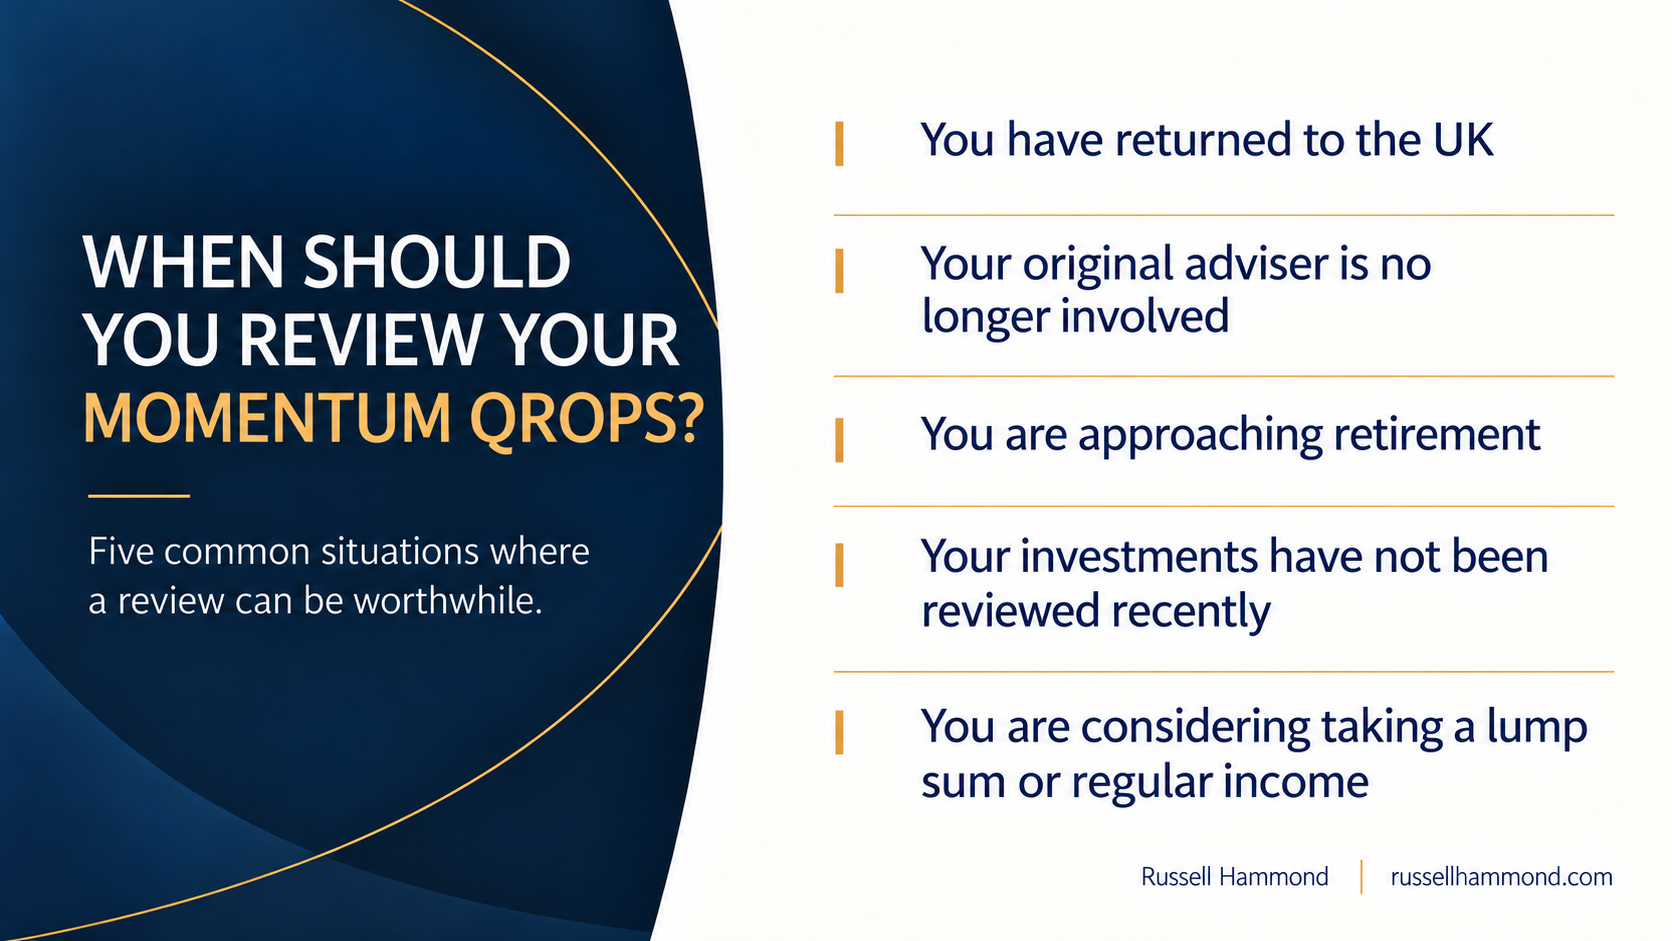
When should you consider reviewing your Momentum QROPS?
There are several circumstances in which a pension review may be particularly worthwhile.
You have returned to the UK
Many QROPS were originally established when their members were living overseas.
Returning to the UK can materially change the financial planning considerations.
For example, the UK taxation of pension withdrawals, inheritance tax exposure, investment arrangements and retirement income requirements may all need to be reconsidered.
However, returning to the UK does not automatically mean that your QROPS must be transferred into a UK SIPP.
Whether to retain an overseas pension or transfer it to a UK arrangement depends on the individual’s circumstances, the existing scheme benefits, charges, investment options and relevant tax rules.
Your original financial adviser is no longer involved
International financial advisers frequently change firms or relocate between jurisdictions.
Consequently, some QROPS members find themselves holding a pension established many years earlier without an adviser who is actively reviewing their circumstances.
If this applies to you, it is worth establishing who is currently responsible for providing investment advice and whether the existing investment strategy remains appropriate.
Momentum may continue to administer the pension, but that should not be confused with receiving personalised financial advice.
You are approaching retirement
The investment strategy that was suitable when you were accumulating retirement savings may no longer be appropriate when you begin taking withdrawals.
At this stage, considerations include:
- How much income you need from your pension.
- Whether to take a pension commencement lump sum.
- The appropriate balance between equities, bonds, alternatives and cash.
- How to manage investment volatility while making withdrawals.
- The taxation of pension income in your country of residence.
- How your QROPS fits alongside other pensions and investments.
For clients approaching retirement, I place particular emphasis on sustainable withdrawals and ensuring that sufficient liquidity is available to meet foreseeable income requirements.
Your investments have not been reviewed recently
A pension’s underlying investment portfolio should reflect your current circumstances and capacity for risk.
Some longstanding QROPS arrangements contain investments selected many years ago, and it is sensible to review whether those holdings remain suitable.
My investment philosophy is centred on diversified, evidence-based portfolios, with a particular focus on asset allocation, controlling costs and avoiding unnecessary complexity.
Where the existing investment arrangements remain suitable, there may be no reason to change them. Where improvements are appropriate, the first step should be to establish whether they can be implemented within the existing Momentum pension.
You are considering taking a pension lump sum or regular income
QROPS withdrawals require particular care because the applicable rules can depend on the pension jurisdiction, the origin of the pension funds and the member’s tax residence.
For example, the treatment of UK tax-relieved funds can differ from funds derived from non-UK pension contributions.
Where a scheme contains different categories of pension benefits, accurate records and the appropriate segregation of those funds can be especially important.
The amount that may be paid under the pension scheme’s rules is also not necessarily the amount that will be free from tax in the member’s country of residence.
Before making substantial withdrawals, I therefore consider both the pension benefit rules and the wider tax consequences.
Should you retain your Momentum QROPS or transfer to another pension?
This is an important question, and one that should be assessed on its merits.
There are circumstances in which transferring an existing QROPS to a UK SIPP or another suitable pension arrangement may make sense.
However, a transfer is not automatically beneficial simply because an individual has changed country or wishes to appoint a new adviser.
An existing Momentum QROPS may already offer suitable investment options, an appropriate pension structure and the retirement flexibility required.
A transfer could also introduce new administration, investment costs, tax considerations or the loss of existing arrangements that may be worth preserving.
For that reason, I generally begin by examining whether the client’s objectives can be achieved within the pension they already hold.
If the existing arrangement remains suitable, I see little merit in introducing additional complexity without a clear benefit.
The appropriate solution should be determined by the client’s financial circumstances rather than a preference for any particular pension product or provider.
Retirement planning should extend beyond the pension itself
A QROPS is only one component of an individual’s financial position.
Effective retirement planning also involves understanding other assets, pensions, investments, property, cash reserves and future expenditure requirements.
When advising clients, I use financial cash-flow modelling to examine how their wealth might support their desired lifestyle over the coming decades.
This allows us to consider questions such as:
- How much can I sustainably withdraw?
- What happens if investment markets fall significantly?
- Should I take pension benefits now or defer them?
- How should I coordinate withdrawals from different investments?
- How might future inflation affect my retirement income?
- What financial provision should I make for my spouse or beneficiaries?
These considerations are particularly relevant to internationally mobile individuals whose pension and investment arrangements may span several jurisdictions.
Working with an existing Momentum QROPS
Having worked with Momentum pension arrangements over many years, I am familiar with the practical and technical considerations involved in advising existing members.
I am a Chartered Financial Planner and Chartered Investment Adviser, and my work focuses on helping individuals and families manage substantial retirement and investment assets, particularly where international financial planning is involved.
My approach is to begin with the client’s objectives and existing arrangements rather than assuming that a pension transfer or wholesale investment change is required.
For an existing Momentum member, that may involve reviewing the pension and its investments, arranging an adviser change where appropriate, recommending a new investment strategy or developing a retirement income plan.
It may equally involve concluding that the existing arrangements remain suitable and should be retained.
The objective is to ensure that the pension continues to serve its intended purpose: supporting the member’s long-term financial security.
Final thoughts
Momentum has been an established participant in the international pensions market for many years, and its QROPS arrangements continue to be relevant to individuals with overseas pension benefits.
However, a pension established ten or fifteen years ago should not simply be assumed to remain optimally structured for the circumstances of today.
Your country of residence, retirement objectives, investment requirements and wider financial position may have changed considerably.
The encouraging point for existing Momentum QROPS members is that obtaining new financial advice does not automatically require changing pension provider.
Sometimes the most valuable improvements can be made by reviewing and refining the arrangements you already have.
This article provides general information and does not constitute personal financial or tax advice. Pension withdrawal rules, tax treatment and investment suitability depend on individual circumstances and may change. References to Momentum Pensions describe my professional experience with the provider and do not imply that Momentum endorses this article or my advisory services.
Frequently Asked Questions
Can I change the financial adviser on my Momentum QROPS?
Yes. Momentum has procedures for appointing a new financial adviser. The new adviser must satisfy the applicable regulatory and provider requirements. Changing adviser does not ordinarily require the pension itself to be transferred.
Can a UK financial adviser advise me on my Momentum QROPS?
A suitably authorised UK financial adviser may be able to advise on an existing Momentum QROPS. This depends on the advice required, the adviser's permissions, your country of residence and Momentum's adviser appointment requirements.
Should I transfer my Momentum QROPS to a UK SIPP if I return to the UK?
Not necessarily. Returning to the UK does not automatically make a UK SIPP more suitable. The decision should consider charges, investment options, withdrawal flexibility, tax implications and your wider retirement objectives.
Can I withdraw a lump sum from my Momentum QROPS?
Momentum QROPS arrangements offer retirement benefit options, including pension lump sums, subject to the applicable scheme rules. The amount available and its tax treatment depend on your individual circumstances, pension funding history and country of tax residence.
Can I change the investments held within my Momentum QROPS?
Generally, yes, subject to the pension's investment guidelines, available investment providers and trustee approval. An investment review can establish whether your existing holdings remain suitable or whether changes would improve your retirement strategy.
Continue reading
Financial Life Management: Your Personal CFO for Life’s Important Financial Decisions
Financial Life Management: Your Personal CFO for Life's Important Financial Decisions Managing wealth can become surprisingly complicated. You may have built a successful business, accumulated substantial investments, acquired [...]
Moving Back to the UK with a QROPS? Your Complete Guide
Returning to the UK after living overseas can raise a number of important financial planning questions, particularly if you hold pension benefits within a Qualifying Recognised Overseas Pension Scheme [...]
Transfer a Gibraltar QROPS to a UK SIPP: Rules, Tax and Drawdown
If you have a pension held in a Gibraltar Qualifying Recognised Overseas Pension Scheme (QROPS), you may be surprised to discover that the rules governing withdrawals are quite different [...]