Been Recommended an Offshore Bond from RL360? Read This First.
Key takeaways
1. RL360 offshore investment bonds can offer tax deferral, international investment access and useful estate planning flexibility when appropriately structured.
2. The way an RL360 bond is funded and remunerated can have a substantial impact on its overall cost and long-term investment performance.
3. Commission-funded arrangements may involve higher charges and surrender penalties, making it important to understand all costs before proceeding.
4. Fee-based advice can significantly reduce product costs and avoid the need for substantial upfront adviser commissions.
5. Before accepting an RL360 recommendation, seek a transparent breakdown of charges, surrender conditions and the ongoing service you will receive.
Is an RL360 Bond the Right Fit for You? Here’s What to Consider First
If you’ve recently been recommended an offshore investment bond from RL360, it’s worth taking a few minutes to understand exactly what’s being proposed — and how it could impact you long-term.
Offshore bonds can be a powerful tool for British expats and international investors. But the way they’re often sold — particularly when commission is involved — can lead to unnecessarily high costs, limited flexibility, and poor long-term outcomes.
The Good News: Offshore Bonds Can Offer Real Benefits
When structured correctly, RL360 bonds can provide:
-
Tax deferral: Investment growth without immediate tax liability
-
Access to global investments: Including funds, model portfolios, and discretionary services

-
Multi-currency options: Helpful for globally mobile investors
-
Succession planning advantages: Including trust planning and assignment
-
Potential UK tax efficiency: Via 5% annual tax-deferred withdrawals
In the right hands, these bonds can form part of a well-structured international financial plan.
The Problem: How They’re Usually Sold
The most common issue with RL360 bonds isn’t the product itself — it’s how it’s typically sold (outside of the UK).
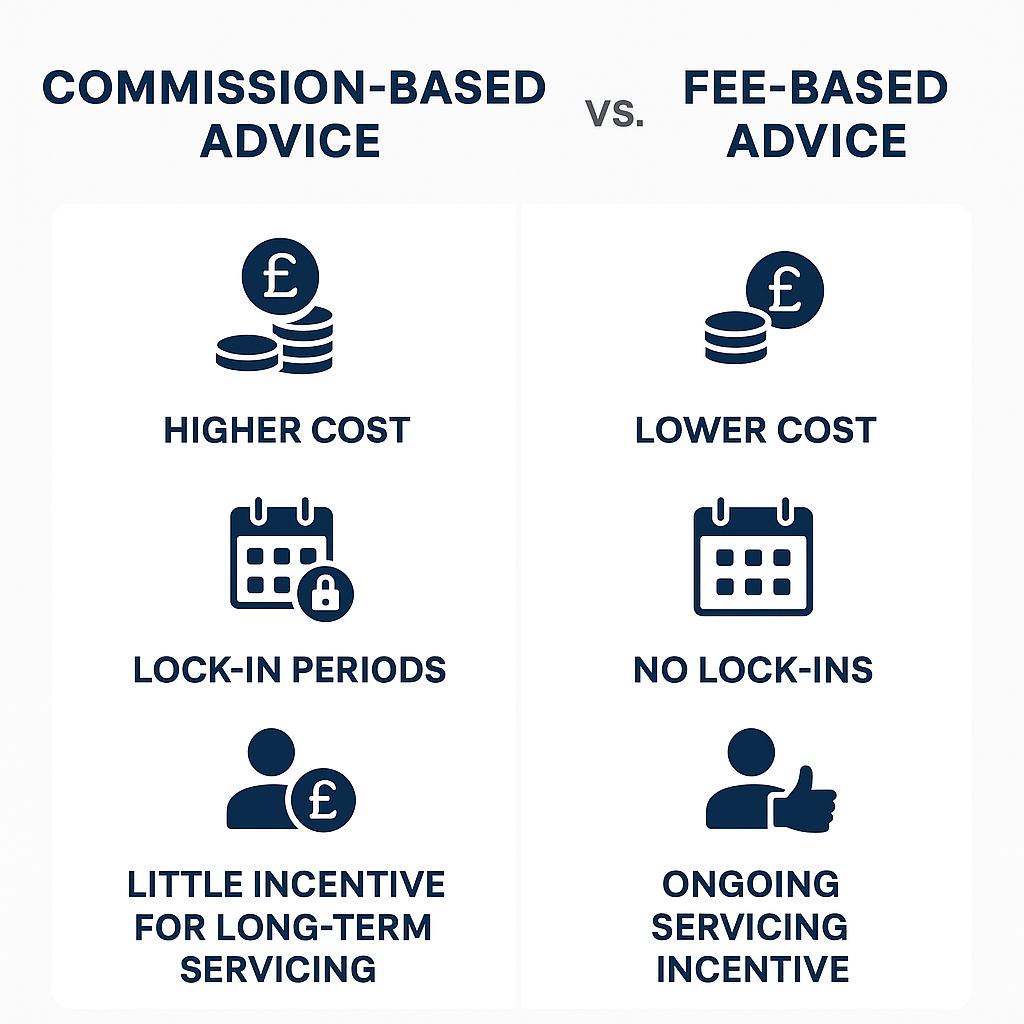
Many RL360 products are recommended by advisers who are paid 5–7% upfront, plus annual trail commissions. These commissions are embedded into the bond’s structure, often without the client realising.
As a result, you may face:
-
High annual product costs
-
Early exit penalties or lock-in periods of 5–10 years
-
Limited investment flexibility
-
Lower long-term returns due to internal cost drag
Even worse, once the bond is set up, the adviser is usually not incentivised to provide ongoing support — because they’ve already been paid upfront. Clients are sometimes left on their own, with no proactive help managing or adjusting their investments as circumstances change.
The Same RL360 Bond Can Be 90% Cheaper via Fee-Based Advice
Here’s what many investors never discover:
The exact same RL360 product can be up to 90% cheaper when structured through a fee-only adviser rather than on a commission basis.
That’s right:
-
Same product
-
Same investment access
-
Radically lower total charges
-
No embedded commission
-
No artificial lock-ins
This means more of your capital stays invested, and you’re far less likely to be tied into an expensive, inflexible structure you later regret.
What Makes MeDifferent
I provide impartial, fee-based advice and am fully UK regulated.
That means:
-
I work solely for you — not for any investment provider
-
I charge transparent, pre-agreed fees
-
I don’t take commissions or hidden payments
-
My advice is structured around your life, not a sales quota
If I recommend a bond — whether from RL360, Utmost or elsewhere — it’s because it genuinely fits your needs, and I’ll structure it in the most cost-effective, transparent way.
Getting Out Later Can Be Expensive — So Get it Right Now
I regularly speak to clients who took out an RL360 bond on commission terms years ago and are now stuck with:
-
High running costs
-
Inflexible structures
-
Significant penalties for early surrender
All of this is avoidable — if you get the advice and structure right from the outset.
Summary
RL360 offshore bonds can offer value — but only when:
-
They are structured without commission
-
The costs are fully transparent
-
You receive genuine, ongoing support from a properly aligned adviser
Before locking into any long-term investment product, ask:
“Is this being recommended because it’s best for me — or because it’s most profitable for the adviser?”
Contact Me Today for a Second Opinion
I regularly review RL360 product recommendations and help clients access more flexible, lower-cost alternatives — or structure the bond properly through a fee-based model that works in their favour.
Ready to make the most of your finances?
Book a free 30-minute consultation via Microsoft Teams at a time that suits you. Let’s explore how I can optimise your investments, pensions, or retirement plans.
Schedule your free, no obligation 30 minute Teams call now
✔ UK-regulated advice
✔ Fee-only, client-first model
✔ Ongoing support, no commissions, no lock-ins
Frequently Asked Questions
Are RL360 offshore investment bonds a good investment?
RL360 offshore investment bonds can be suitable for internationally mobile investors seeking tax deferral, multi-currency investment access and estate planning flexibility. However, suitability depends on your circumstances, tax residence, investment objectives and the charges associated with the particular bond. An appropriate product can still represent poor value if unnecessarily expensive commission arrangements are used.
What charges apply to an RL360 offshore bond?
RL360 bond charges vary depending on the product and how it was established. They may include policy administration charges, investment fund costs, adviser remuneration and early surrender charges. Some commission-funded arrangements contain additional costs designed to recover upfront payments made to the adviser. Request a complete breakdown of all charges before proceeding.
Can an RL360 offshore bond be arranged without commission?
Yes. Certain RL360 offshore bond arrangements can be established on a fee-based basis, avoiding substantial upfront adviser commissions. This can materially reduce overall costs and improve flexibility. The available charging structure depends on the specific product, distribution arrangements and jurisdiction.
Are there penalties for surrendering an RL360 bond early?
Some RL360 offshore investment bonds impose surrender charges during an initial charging period. The amount depends on the product, policy terms and time elapsed since inception. Not all RL360 bonds have the same surrender conditions, so it is important to examine your specific policy documentation before making a withdrawal or surrendering the investment.
Should I get a second opinion before investing in an RL360 offshore bond?
Obtaining a second opinion is sensible, particularly where you have been recommended a long-term investment arrangement with significant charges or surrender restrictions. A review can establish whether the proposed bond is appropriate, whether charges are competitive and whether a more flexible or cost-effective solution is available.
Continue reading
Moving Back to the UK with a QROPS? Your Complete Guide
Returning to the UK after living overseas can raise a number of important financial planning questions, particularly if you hold pension benefits within a Qualifying Recognised Overseas Pension Scheme [...]
Utmost International Offshore Bond: What to Know Before You Invest
Utmost International Offshore Bonds: Understanding the Opportunities and Considerations Utmost International is an established, market-leading provider of offshore investment bonds, offering solutions for UK residents, internationally mobile individuals and [...]
Want to Change Your RL360 Adviser or Get a Second Opinion?
If you hold an RL360 investment bond and are considering changing financial adviser, you’re not alone. Many RL360 policyholders originally established their bond years ago, often whilst living [...]