Gifting an Offshore Bond to Your Children: Assignments, Tax and What to Consider
Key takeaways
- A gift assignment can avoid an immediate chargeable event. A genuine gift and an assignment for value have different tax treatment.
- The tax history follows the policy. Original premiums, withdrawals and earlier gains remain relevant after a gift.
- Whole segments need careful allocation. Confirm their actual values and histories with the insurer before giving instructions.
- Ownership and control pass to your child. Start with affordability and your wider family plan.
- Inheritance tax needs a separate review. The seven-year rule and special policy valuation rules cannot be reduced to a simple calculator.
Helping your children with a home, a career change or the next stage of family life can be one of the most rewarding uses of your wealth. If you hold an offshore investment bond, you may have another option alongside withdrawing cash: gifting ownership of individual policy segments.
A genuine gift assignment can normally take place without an immediate UK chargeable event. But that does not make the bond’s accumulated growth disappear, and it does not automatically make the gift the right decision.
This guide explains the questions UK families should address before assigning an offshore bond to adult children, and includes an illustrator to explore how whole segments could be allocated.
Can you gift an offshore bond to your children?
Many offshore investment bonds are written as a collection of individual policies, often called segments. Subject to the contract and insurer’s requirements, an assignment transfers ownership of specified policies to someone else. A gift assignment involves no payment or other consideration.
HMRC distinguishes a gift from an assignment for money or money’s worth. A gift is normally not a chargeable event for income-tax purposes, whereas an assignment for value can be. The legal documents and the underlying beneficial ownership matter: adding a name to paperwork is not a substitute for completing the intended transfer. See HMRC’s guidance on assignments.
This article considers outright gifts to adult children. Gifts involving minors, trusts, joint ownership, business arrangements or any payment need separate legal and tax advice.
Gifting cash or assigning segments: why the order matters
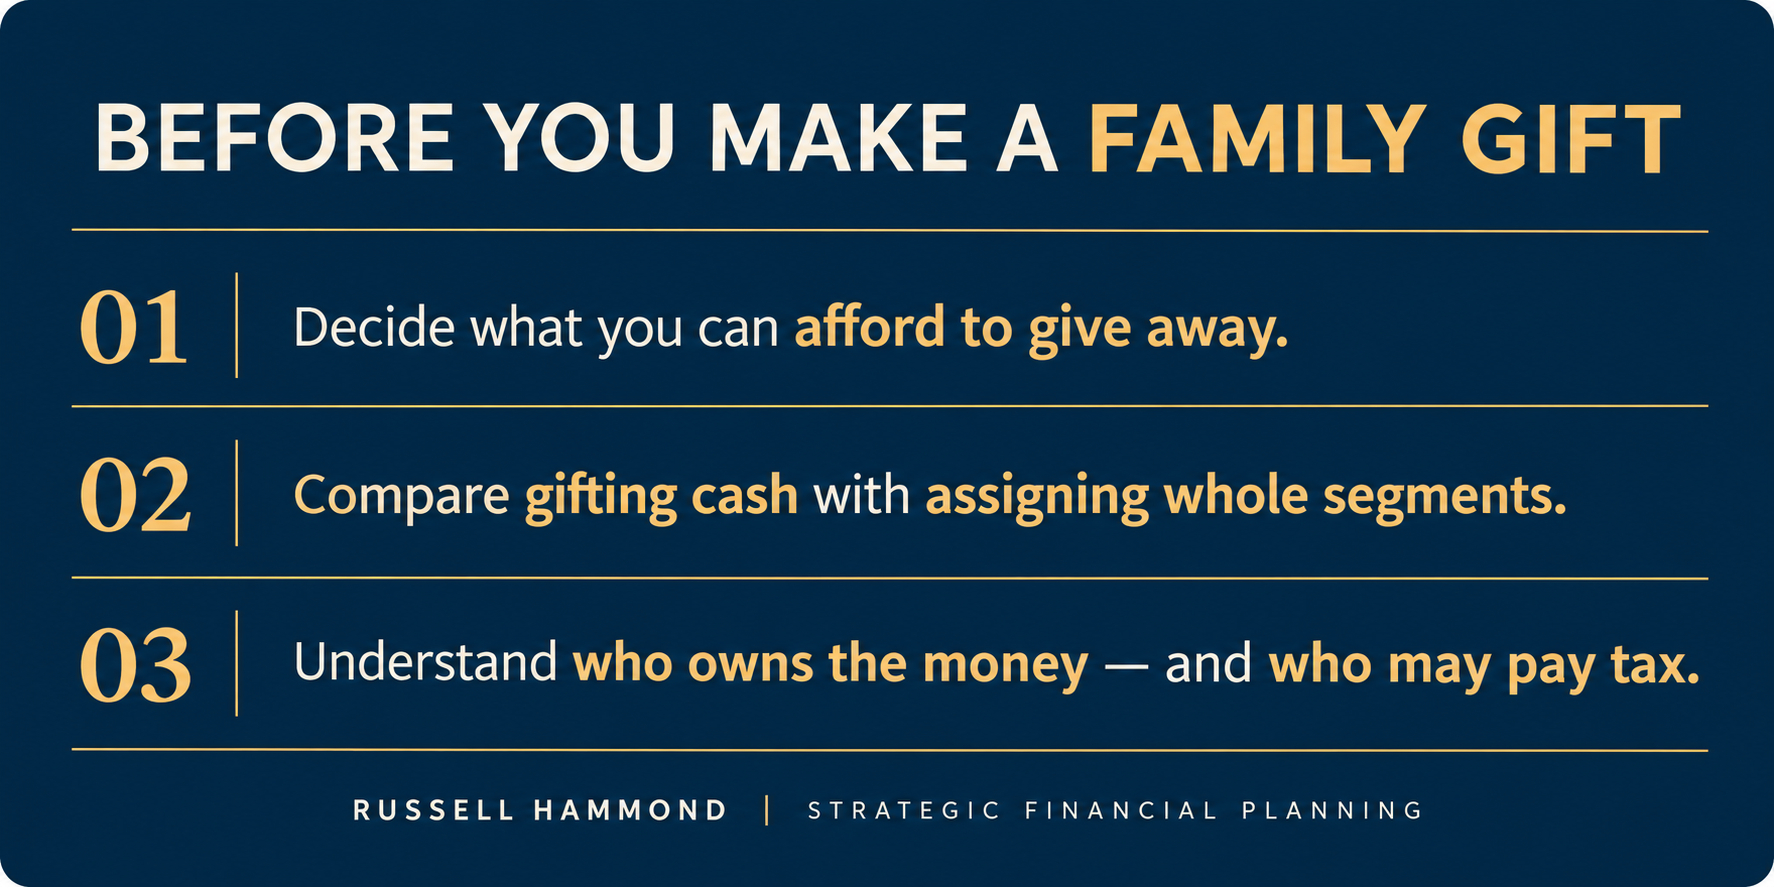
There are two different decisions: how you raise or transfer the money, and who owns the investment when a later taxable event occurs. These should be planned together.
| Approach | What happens | Question to resolve |
|---|---|---|
| Withdraw cash, then gift it | You take money from your bond and give cash to your child. | What chargeable event, if any, arises for you from the withdrawal or surrender? |
| Gift whole segments | Your child becomes the owner of the assigned policies. | What could happen when they later surrender, withdraw from or otherwise dispose of them? |
| Retain ownership for now | You keep the investment and control of future access. | How does the bond fit your own retirement needs and wider estate plan? |
Requesting a partial withdrawal across every segment can produce a different tax outcome from fully surrendering selected segments. Ask the insurer to illustrate the alternatives before submitting instructions. An offshore bond review can also check charges, investments and whether the policy remains suitable.
The tax history does not reset when you make a gift
Your child does not simply start with a new bond whose premium equals the value on the gift date. The original premium and previous policy transactions remain relevant to a later gain calculation. Previous withdrawals and earlier chargeable gains can change the result. Obtain a full policy history rather than estimating tax from today’s value less the amount originally invested.
A chargeable-event gain on a foreign life insurance policy is generally assessed as income, not a capital gain. The capital-gains annual exemption is therefore not the relevant allowance. Foreign policies normally do not carry the UK basic-rate tax credit associated with many UK policies. HMRC’s foreign-policy helpsheet explains the framework.
The person liable for a later event depends on the ownership and applicable rules at that time. For an outright gift to an adult child, their circumstances may be relevant to the eventual liability. Their other income, tax residence and timing of access must be considered; a lower salary alone does not establish the tax cost.
Top slicing relief is not an automatic exemption
Top slicing relief may reduce the income tax on a qualifying gain. It is a calculation of tax relief, not a way to spread the actual gain across past tax returns. The number of years and the individual’s circumstances matter. A gift does not by itself guarantee relief or a tax saving. See HMRC’s explanation of top slicing relief.
A worked example: allocating a £150,000 gift
Suppose a bond is worth £500,000 and consists of 100 remaining segments, each with the same value and premium history. Each segment is worth £5,000. The parent wants to gift £150,000 equally to two adult children.
- 30 whole segments represent £150,000 at the assumed current value.
- Each child receives 15 segments, worth £75,000.
- The parent retains 70 segments, worth £350,000.
If the original premium attributable to those 100 remaining segments is £300,000, the premium allocation attached to each child’s 15 segments is £45,000. That is historical record information, not a £45,000 tax-free withdrawal allowance. This example does not calculate a chargeable gain, tax liability or inheritance-tax value, and ignores charges and market movement.
Explore your own family gift
Use the illustrator below to translate a proposed total gift into whole segments. It rounds down to stay within your chosen budget and shows how an uneven number of segments could be distributed. If the real segments have different values or histories, ask the insurer for an individual segment schedule instead.
Offshore Bond Family Gifting Illustrator
Explore how a proposed gift could be divided into whole segments among adult beneficiaries.
Assumes all remaining segments have equal values and equal premium histories. Figures are illustrative current values, not guaranteed proceeds. Confirm the actual segment records and assignment terms with your insurer.
This illustrates allocation only. It does not calculate a chargeable gain, income tax, top slicing relief, an inheritance-tax valuation or any tax saving. Previous withdrawals, residence, trusts and individual circumstances need separate advice. Values stay in your browser.
What about inheritance tax?
An outright gift to an individual is normally a potentially exempt transfer. Broadly, it can fall outside your estate if you survive seven years, subject to the relevant rules and exemptions. Retaining a benefit can undermine the intended treatment. Taper relief, where applicable, reduces tax on a taxable gift; it does not simply reduce the value of every gift after three years. See the government’s guide to gifts and inheritance tax.
There is a further reason not to treat the illustrator as an inheritance-tax calculator: special valuation rules can apply to lifetime transfers of life policies. In some circumstances the relevant value can exceed the current surrender value. The policy type and its history need checking against HMRC’s life-policy valuation guidance.
Inheritance-tax planning should also consider previous gifts, your estate, who bears any tax and whether you need the capital later. A gift should be affordable even if investment returns disappoint or your care and living costs rise.
Once ownership changes, control changes too
An outright gift belongs to your child. They may choose a different investment strategy or cash in the policy sooner than you expect. Their relationship, financial pressures and future plans may change. Discuss the purpose of the gift openly, but do not assume a family understanding gives you continuing legal control.
If you want to set conditions, preserve access or provide for younger beneficiaries, explore the alternatives before making an outright assignment. A trust is a separate planning decision with its own legal, tax and administration consequences; it is not a simple extra box on an assignment form.
What to check before signing an assignment
- Your own financial security. Model retirement spending, emergencies and the effect of losing access to the proposed gift.
- The exact policy structure. Confirm remaining segments, ownership, lives assured, restrictions and whether assignment is permitted.
- The full transaction history. Obtain premiums, withdrawals, previous gains and any earlier assignments. Keep insurer statements and certificates.
- The recipient’s plans. Discuss when money may be needed, their residence and likely income at that time.
- The documentation and sequence. Confirm the deed, insurer registration, effective ownership and any later surrender instructions with the relevant professionals.
- The wider family plan. Record the gift, consider wills and other beneficiaries, and review the inheritance-tax position.
How I can help you assess the options
I help families understand how offshore bonds fit within their wider wealth, retirement and succession plans. With more than 20 years’ experience, my approach to Strategic Financial Planning starts with what the money needs to achieve for you and your family.
We can review the existing policy, compare practical routes and coordinate with your tax and legal advisers before instructions are submitted. If you are exploring the structure for the first time, start with my guide to offshore investment bonds.
Thinking about gifting an offshore bond? Book a consultation to discuss the policy and the family goals behind the gift.
This article provides general information, not a personal recommendation or tax or legal advice. Tax treatment depends on individual circumstances and legislation and practice can change. Investments can fall as well as rise, and you may get back less than you invest. Offshore bonds are not suitable for everyone. Obtain advice before assigning, withdrawing from or surrendering a policy.
Frequently Asked Questions
Can I gift an offshore bond to my adult children without paying tax immediately?
A genuine gift assignment is normally not a UK chargeable event for income-tax purposes. This does not erase the bond’s tax history or guarantee that later access will be tax-free. Confirm the policy terms, ownership and documentation before acting.
Does my child’s offshore bond start again at its value on the gift date?
No. A gift does not normally reset the policy’s original premium or transaction history. Premiums, previous withdrawals and earlier chargeable gains can affect a later gain calculation. Ask the insurer for full records.
Is it better to gift cash or assign whole bond segments?
It depends on your policy, your own tax position and your child’s circumstances and plans. Raising cash first may create a taxable event for you; assigning segments changes ownership before any later event. Compare the alternatives before submitting instructions.
Does gifting an offshore bond remove it from my estate immediately?
An outright gift to an individual is normally a potentially exempt transfer. Broadly, surviving seven years can take it outside your estate, subject to applicable rules, exemptions and any retained benefit. Special life-policy valuation rules may also apply.
Does the family gifting illustrator calculate tax savings?
No. It illustrates how a total gift could be allocated among adult beneficiaries using whole, equally valued segments with equal premium histories. It does not calculate income tax, chargeable gains, top slicing relief, an inheritance-tax valuation or tax savings.
Continue reading
Want to Change Your RL360 Adviser or Get a Second Opinion?
If you hold an RL360 investment bond and are considering changing financial adviser, you’re not alone. Many RL360 policyholders originally established their bond years ago, often whilst living [...]
Been Recommended an Offshore Bond from RL360? Read This First.
Is an RL360 Bond the Right Fit for You? Here's What to Consider First If you’ve recently been recommended an offshore investment bond from RL360, it’s worth taking a [...]
Offshore Bond UK Return: Save Tax Before Moving Back to the UK
What you need to know before becoming UK tax resident again If you're a British expat planning to return to the UK, now is the time to consider your [...]