Financial Planning for British Expats in Switzerland: What the Berne Agreement Means for You
Key takeaways
• Swiss eligibility requires at least CHF 2 million in qualifying assets and a professional-client election.
• Berne concerns financial services access, not changes to personal taxation.
• Coordinate UK pensions, Swiss investments, currencies, retirement and family priorities.
For many British expats in Switzerland, financial success brings a particular challenge: wealth builds up across two countries, but the planning around it remains fragmented. A Swiss investment portfolio, UK pensions, property and family commitments may each be well managed, while nobody has a clear view of how they work together.
The Berne Financial Services Agreement, which is now in force, makes this a timely moment to revisit that wider picture. For eligible high-net-worth clients in Switzerland, it simplifies certain arrangements for accessing investment services from qualifying UK firms.
What does the Berne agreement change?
The agreement establishes a framework for mutual recognition in specified financial services between the UK and Switzerland. For qualifying UK investment firms, it removes the need for individual client advisers to register with Swiss registration bodies when providing covered services temporarily in Switzerland, subject to the agreement’s conditions.
The firm must meet eligibility requirements, notify the FCA and provide the required client disclosures. FCA authorisation alone does not automatically establish eligibility to use this route. Nor does the agreement cover every financial service or remove all Swiss requirements.
For an expatriate, the practical relevance is access to appropriately qualified UK expertise where the relevant conditions are satisfied.
Who qualifies for the CHF 2 million route?
The agreement’s Swiss high-net-worth category covers eligible individuals and certain private investment structures with at least CHF 2 million in qualifying assets who declare that they wish to be treated as professional clients.
This is different from the reverse route, where Swiss firms serve qualifying UK clients with net assets exceeding £2 million. The currencies and asset definitions differ.
Under the Swiss asset rules, qualifying financial investments include bank deposits, securities, funds and certain other investments. Direct property holdings, social insurance entitlements and occupational pension assets are excluded. A headline household net-worth figure is therefore insufficient to establish eligibility.
Professional-client status also affects the protections and assumptions that apply to the relationship. The implications should be explained before making that election.
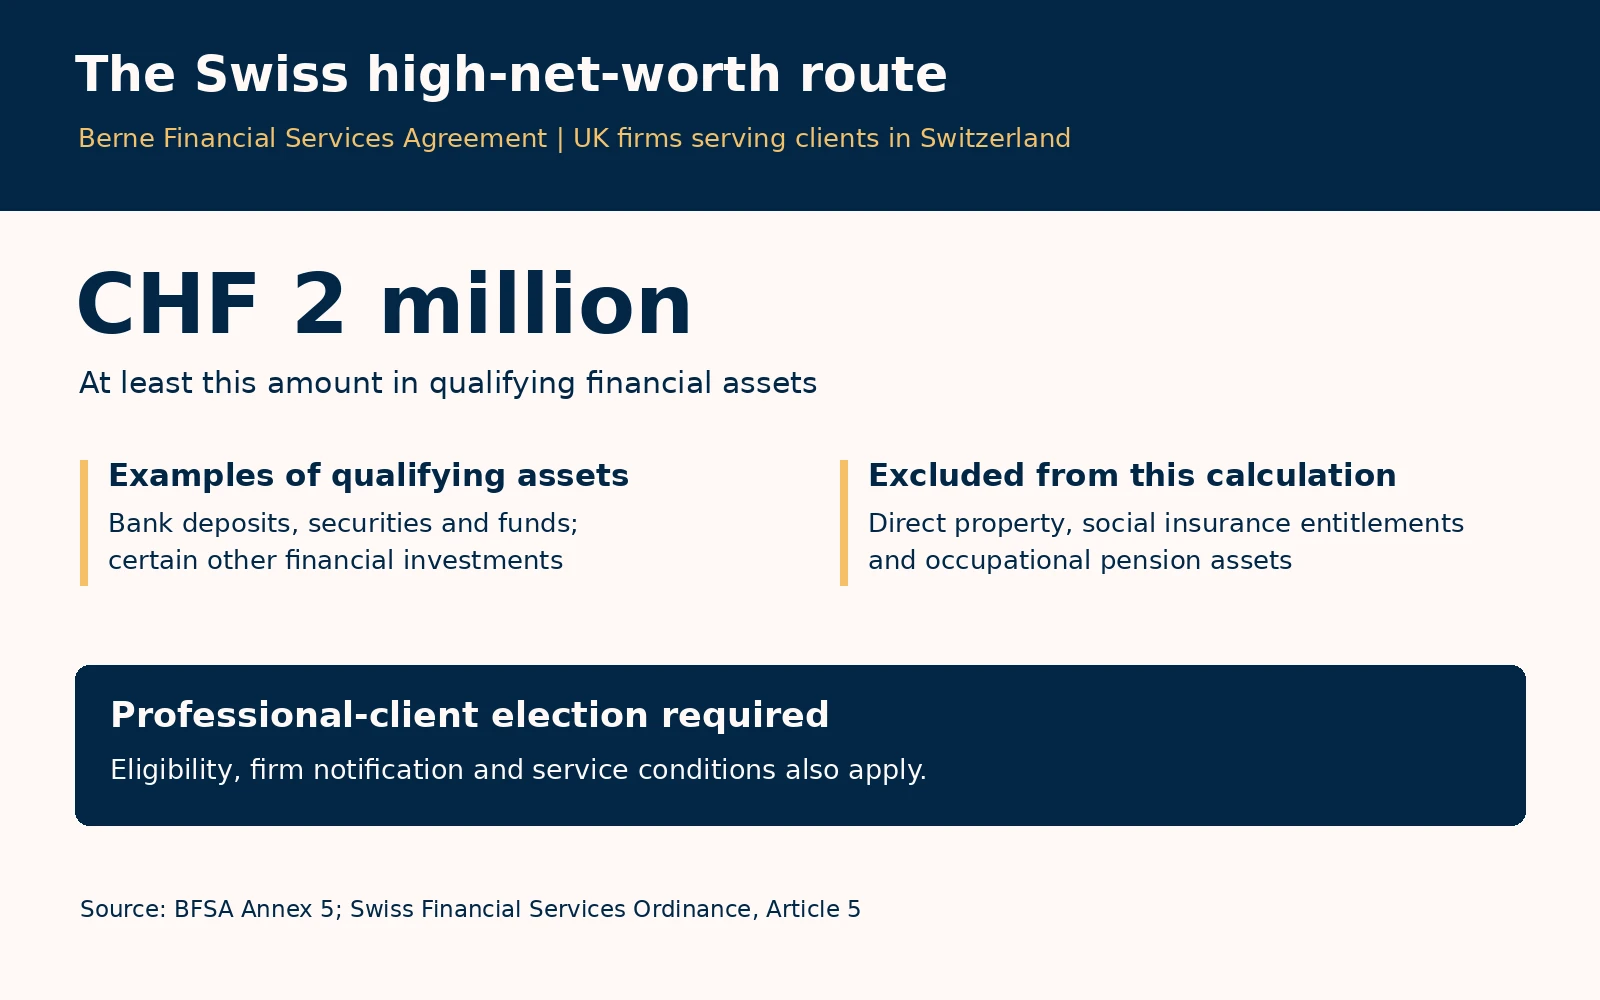
The Swiss high-net-worth route
CHF 2 millionAt least this amount in qualifying financial assets.
Qualifying assetsBank deposits, securities and funds; certain other financial investments.
Excluded assetsDirect property, social insurance entitlements and occupational pension assets.
Professional-client electionRequired, alongside the applicable firm notification and service conditions.
Source: BFSA Annex 5; Swiss Financial Services Ordinance, Article 5.
A Swiss portfolio is one part of the picture
You may already have a strong relationship with a Swiss bank or investment manager. The wider planning question is how that portfolio supports everything else you want to achieve.
Can you retire when you would like? How much can you spend comfortably? Which assets would fund a return to Britain? How would your spouse manage the arrangements if you died? These questions require a coordinated view of your finances.
This is where Strategic Financial Planning becomes valuable: giving each account, investment and pension a clear purpose within an overall plan.
Bring your UK and Swiss finances together
RetirementReview UK pensions alongside Swiss provision. Decide when and how income will be needed.
CurrenciesMatch cash needs to future expenditure, considering sterling and Swiss francs.
Future residenceCompare staying in Switzerland with a UK return before making commitments.
Family prioritiesConnect investments with family goals and coordinate with tax and legal specialists.
One plan. Clear priorities. Regular reviews.
Review UK pensions in their wider context
UK pensions often represent a substantial part of an expatriate’s wealth. They should be reviewed alongside Swiss retirement provision, accessible investments and expected future expenditure.
The starting point is understanding what you already hold: benefits, guarantees, charges, investments and withdrawal options. A review should not assume that a transfer is necessary simply because you live overseas.
Before taking benefits, establish the applicable UK and Swiss treatment, including the relevant treaty provisions. Berne is a financial services agreement; it does not make a withdrawal tax-free. My guide to UK pensions for expats explains the broader questions to consider.
Plan for spending in francs and sterling
Someone expecting to remain in Switzerland may have very different spending needs from someone planning to retire in the UK. Family support, school fees or property commitments can add further currencies.
The currency shown on an investment statement tells only part of the story. The underlying assets, near-term cash requirements and currency of future expenditure all matter.
A useful plan identifies which assets will fund which commitments, then considers how much currency uncertainty you can afford. Converting everything at once is rarely a substitute for that analysis.
Keep a possible UK return in view
Even a tentative return to Britain deserves a place in the plan. Decisions about investments, withdrawals, property and gifts can have different consequences depending on your residence and their timing.
The sensible approach is to model the alternatives before committing. What would retirement in Switzerland cost? What would change if you returned to the UK in five years?
Cashflow modelling can help compare those scenarios, while specialist tax advice establishes the consequences of the proposed steps.
What coordinated planning looks like
Illustrative example: A British couple living in Zurich hold CHF 2.5 million in accessible cash and investments, alongside UK pensions and a Swiss home. They are considering retiring in Britain within seven years.
A useful review would separate service-access eligibility from retirement planning. It would assess qualifying assets, map future spending, examine existing pensions and compare staying in Switzerland with returning to the UK.
The result might involve retaining several existing arrangements. The value lies in knowing how they fit together, what needs attention and when decisions should be made. This example is hypothetical and is not a recommendation.
Bringing your financial life together
With more than 20 years’ professional experience, my approach begins with your objectives and the relationships between your assets, rather than a particular product.
If you are a British expat in Switzerland with substantial investments and UK financial ties, an initial conversation can establish your priorities and whether an appropriate advice service is available for your circumstances. Any engagement is subject to jurisdictional permissions, client classification and the scope of the services required.
Explore how I work and my approach to cross-border financial planning.
Summary
Berne provides a useful reason to review your access to advice. The lasting benefit comes from a clear plan connecting your UK and Swiss finances with the life you want to fund.
References
- HM Treasury: Berne Financial Services Agreement, including Annex 5
- FCA: Berne Financial Services Agreement for UK and Swiss firms
- Swiss Financial Services Ordinance: Article 5, qualifying assets
This article provides general information, not personal financial, legal or tax advice. Eligibility and the availability of services depend on individual circumstances and applicable rules. Investment values can fall as well as rise.
Frequently Asked Questions
Is Berne only relevant to British citizens?
No. The relevant provisions concern client location, classification and qualifying services. British nationality is the focus of this article, rather than an eligibility condition.
Does owning a CHF 2 million home qualify me?
No. Direct property holdings are excluded from the Swiss qualifying financial investment calculation.
Does the agreement change UK or Swiss tax rules?
No. It concerns financial services access and regulatory recognition. Tax treatment requires separate analysis.
Must I move my money to the UK?
The agreement itself does not require that. The location and structure of your investments should follow a suitability assessment.
Can every UK adviser use the agreement?
No. The firm, adviser, client and services must fall within the relevant provisions, with applicable notifications and disclosures completed.
Continue reading
Utmost International Offshore Bond Review for Policyholders
Already own an Utmost bond? Review your charges, adviser and withdrawal options before you surrender it. Book a free call with Russell Hammond.
Moving Back to the UK with a QROPS? Your Complete Guide
If you’re returning to the UK with a QROPS, you can generally keep your existing pension or explore a transfer to a UK self-invested personal pension (SIPP). A transfer [...]
Utmost International Offshore Bond: What to Know Before You Invest
Utmost International Offshore Bonds: Understanding the Opportunities and Considerations Utmost International is an established, market-leading provider of offshore investment bonds, offering solutions for UK residents, internationally mobile individuals and [...]