Utmost International Offshore Bond: What to Know Before You Invest
Key takeaways
- Utmost offshore bonds can offer valuable tax-planning benefits. These include tax deferral, multi-currency investment options, flexible withdrawals and opportunities for estate and succession planning.
- The charging structure can make an enormous difference. Commission-based arrangements may include higher ongoing charges and early surrender penalties, whereas transparently priced, fee-based structures can be considerably more cost-effective.
- The 5% withdrawal allowance is tax-deferred, not tax-free. UK residents can ordinarily withdraw up to 5% of the original investment annually without triggering an immediate chargeable event gain, subject to the cumulative allowance and relevant tax rules.
- How the bond is established matters as much as the investments. Decisions concerning life assurance versus capital redemption, policy segmentation, ownership and lives assured can have significant long-term consequences.
- A second opinion can be extremely valuable. Before establishing or surrendering an Utmost bond, reviewing the total charges, exit penalties, tax implications and investment strategy can help avoid expensive mistakes.
Utmost International Offshore Bonds: Understanding the Opportunities and Considerations
Utmost International is an established, market-leading provider of offshore investment bonds, offering solutions for UK residents, internationally mobile individuals and families seeking to manage, preserve and pass on wealth. Utmost have consistently won awards for their arrangements, their offshore international portfolio bonds in particular.
I’ve advised clients on offshore investment bonds for more than 20 years, including substantial portfolios held with Utmost International and its predecessor businesses, among other providers.
In my experience, an offshore bond can be an extremely effective financial planning tool, particularly for tax deferral, investment management, retirement income and intergenerational wealth planning.
However, the benefits depend on more than simply choosing the right provider. The charging structure, underlying investments, ownership arrangements and tax treatment all deserve careful consideration.
In this article, I’ll explain where Utmost offshore bonds can add value, what to consider before investing and how to ensure the arrangement supports your wider financial objectives.
Offshore Bonds Can Offer Real Benefits
When used properly, offshore bonds like those from Utmost can provide:
-
Tax deferral: Investment growth rolls up without immediate tax liability.
-
Multi-currency flexibility: Ideal for those with global income or expenses.
-
Succession planning benefits: Useful for estate and trust planning.
-
Access to global investments: Including funds, ETFs, and discretionary portfolios.
-
Potential UK tax efficiency: Via 5% annual tax-deferred withdrawals.
These features are real, and in the right hands, they can be part of a smart, tax efficient financial plan.
Understanding Utmost Offshore Bond Charges and Adviser Remuneration
One of the most important considerations when establishing an Utmost International offshore bond is the charging structure.
The overall cost can vary depending on the particular product, jurisdiction, investment arrangements and how the financial adviser is remunerated.
Historically, some offshore investment bonds, particularly those distributed in international markets, have been established using commission-based charging structures.
These may involve an upfront commission payment to the adviser, financed through charges applied to the bond over a number of years. Depending on the arrangement, this can result in higher ongoing charges or early surrender penalties.
Other arrangements allow for transparent, fee-based advice, without an upfront adviser commission being financed through the policy.
The important distinction is not simply whether commission is involved, but the total cost to the investor, the flexibility of the arrangement and the quality of the financial advice received.
What Charges Should You Consider?
Before establishing an offshore bond, I would ordinarily examine:
- Initial adviser remuneration: Any upfront advice fee or commission associated with establishing the arrangement.
- Ongoing adviser charges: The cost of ongoing financial planning, investment reviews and advice.
- Policy charges: Establishment, administration and other charges imposed by the provider.
- Investment costs: Fund management, discretionary investment management and transaction charges.
- Early surrender penalties: Whether charges apply if the bond is surrendered or withdrawals exceed specified limits.
- Long-term flexibility: Whether the arrangement can accommodate changes in residence, investment strategy or financial circumstances.
Can a Fee-Based Utmost Bond Be More Cost-Effective?
In some circumstances, establishing an Utmost bond through a transparent, fee-based arrangement can result in materially lower overall charges than an alternative commission-funded structure.
However, the comparison must be made on a like-for-like basis, considering the particular product, investments, expected holding period and services provided.
A lower initial charge does not necessarily mean a lower lifetime cost, just as a higher charge does not automatically make a particular arrangement unsuitable.
My approach is to evaluate the complete charging structure alongside the investment, tax and financial planning benefits, so clients can make an informed decision about the most appropriate solution for their circumstances.
How I Advise on Utmost International Offshore Bonds
As a Chartered Financial Planner and Chartered Investment Adviser with more than 20 years’ experience, I help clients understand how offshore investment bonds can support their wider financial planning objectives.
My advice is provided through AES Financial Services Ltd, which is authorised and regulated by the Financial Conduct Authority.
When considering an Utmost offshore bond, my approach includes:
- Financial planning first: Establishing whether an offshore bond is appropriate in the context of your wider assets, income requirements and future plans.
- Transparent charges: Explaining the initial and ongoing costs, including adviser remuneration and underlying investment charges.
- Investment strategy: Building an appropriately diversified portfolio aligned with your objectives and attitude to investment risk.
- Tax and estate planning: Considering the implications of policy ownership, segmentation, lives assured, trusts and future withdrawals.
- Ongoing Financial Life Management: Reviewing the arrangement as your circumstances, financial objectives and tax position change.
I also work with individuals who already hold Utmost International bonds and would like a second opinion on their existing arrangements.
The objective is not simply to recommend an investment product, but to ensure that the decisions made today remain appropriate for your longer-term financial future.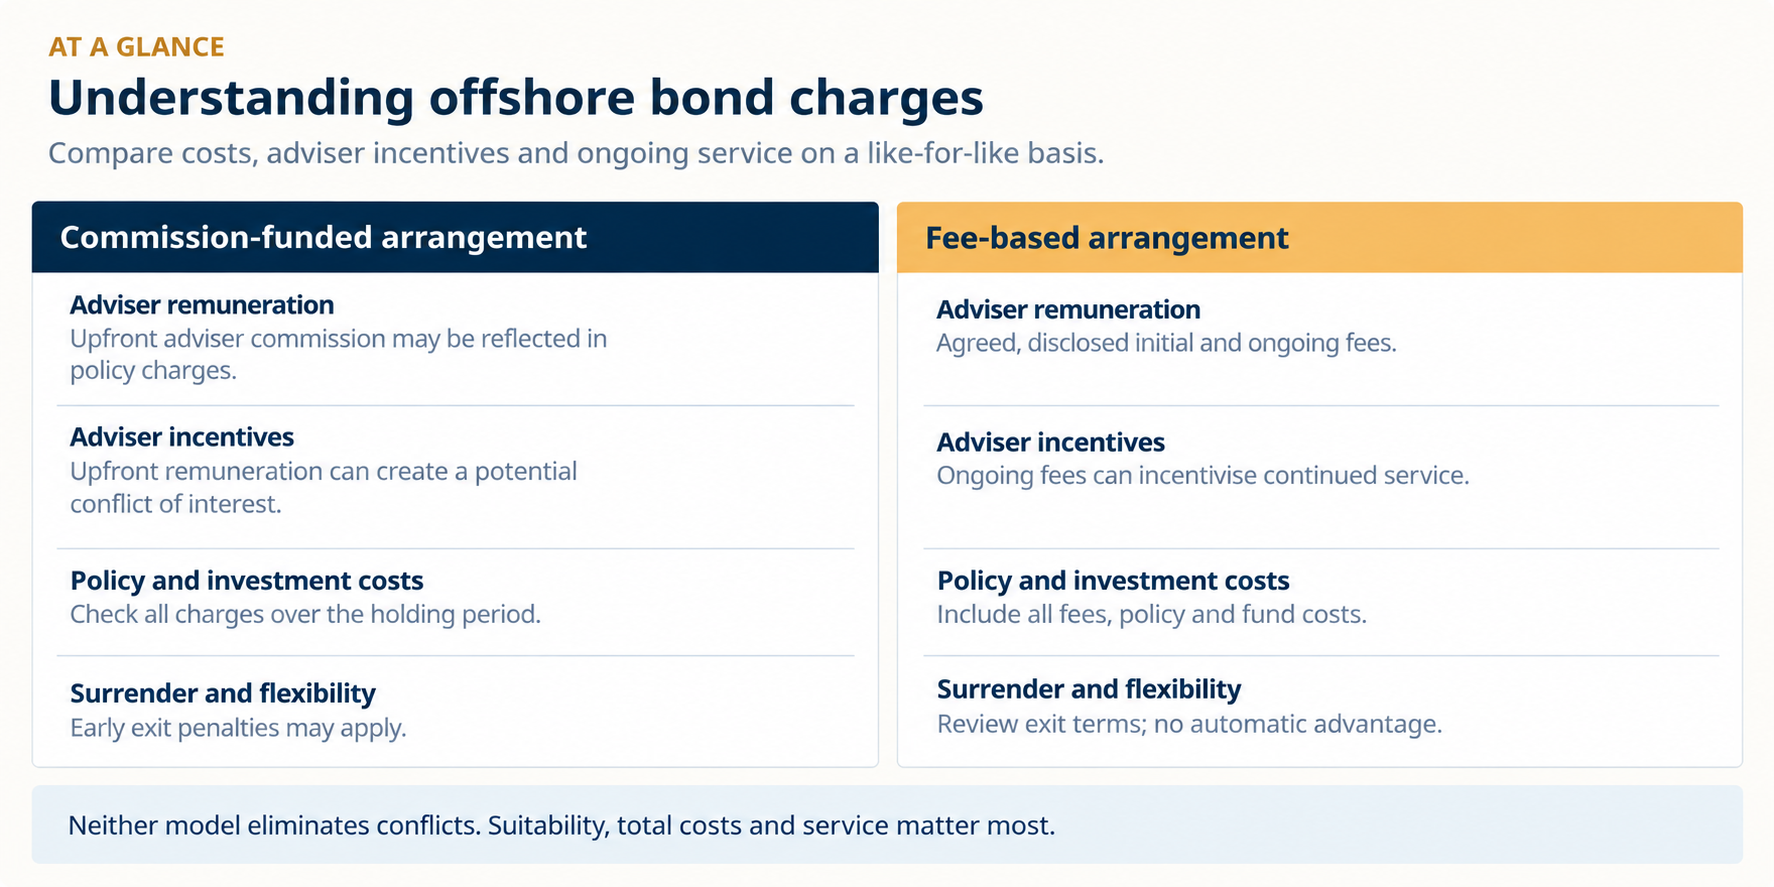
Utmost International Offshore Bonds for Expatriates and Non-UK Residents
Having spent many years advising internationally mobile individuals and families, I have extensive experience of offshore investment bonds held by expatriates and non-UK residents, including clients based in the UAE and other international jurisdictions.
For expatriates, the suitability of an offshore bond depends not only on its investment options and charging structure, but also on the tax rules in their country of residence, their longer-term plans and whether they may eventually return to the UK or relocate elsewhere.
I can help clients review existing Utmost International arrangements and consider how these fit into their wider financial planning, including investment strategy, withdrawal planning, succession and future changes in tax residence.
Where clients live outside the UK, the availability and scope of regulated advice will depend on the relevant jurisdiction and applicable regulatory requirements.
Reviewing an Existing Utmost Offshore Bond
If you already hold an Utmost International offshore bond, it may be worth reviewing the arrangement periodically to ensure that it continues to meet your needs.
Some older policies have charging structures or surrender conditions that differ from those available under more recent arrangements.
However, surrendering or replacing an existing bond is not necessarily the right solution. Doing so may trigger a chargeable event gain, create an unexpected tax liability or result in the loss of valuable existing policy features.
I can help assess the current charges, underlying investments, available withdrawal options and potential tax consequences before recommending whether the bond should be retained or whether any changes are appropriate.
Getting the Structure Right From Day One
The cost of an offshore bond is important, but so is how the bond is actually established.
An Utmost bond can be configured in a number of different ways, and decisions made at outset can have consequences many years later, particularly where the bond is intended to form part of longer-term family or estate planning.
Depending on your circumstances, consideration should be given to:
- Life assurance or capital redemption – whether the bond should ultimately terminate by reference to the death of a life assured, or continue independently of anyone’s lifetime.
- Who should be a life assured – where the life assurance basis is selected, the choice and number of lives assured can materially affect how long the bond can continue.
- The number of policy segments – sufficient segmentation can provide valuable flexibility for future withdrawals, assignments and intergenerational planning.
- Ownership – whether the bond should be held individually, jointly, by trustees or potentially assigned to others later.
- Trust and estate planning – consideration should be given at outset to whether the bond may ultimately form part of a wider gifting, succession or trust strategy.
- Currency and investment structure – the appropriate bond currency, underlying investments and investment management arrangements should reflect the investor’s wider circumstances.
These can look like relatively small administrative choices when the bond is established. In reality, they can determine how flexible the arrangement remains decades into the future.
A well-structured offshore bond should therefore be designed not simply around where you are today, but around how your wealth may need to be held, accessed and ultimately passed on in the future.
Summary
Offshore bonds can be an extremely useful part of a successful financial plan, but only when:
- They are structured correctly from the outset, with your current and future circumstances in mind
- The charging model works for you, not against you
- The underlying investment strategy is appropriate
- And the advice you receive is genuinely impartial and ongoing
Before establishing an offshore bond, the most important question is:
Does this arrangement provide the right combination of tax efficiency, investment flexibility, cost-effectiveness and long-term financial planning benefits for my circumstances?
That is the question I aim to answer when advising clients on Utmost International offshore bonds.
Specialist Advice on Offshore Bond Withdrawals
One of the most overlooked aspects of offshore bond planning is how best to withdraw money from an existing policy.
Although considerable attention is often given to establishing offshore bonds, investors may receive relatively little guidance on how to access their investments tax-efficiently.
The way withdrawals are structured can make a substantial difference to the resulting tax liability. Important considerations include:
- 5% tax-deferred withdrawals – understanding how the accumulated allowance works and the longer-term tax implications.
- Partial withdrawals versus surrendering individual policy segments – assessing which approach is likely to produce the most favourable tax outcome.
- Assignment of policy segments – exploring opportunities to transfer segments to spouses or other family members as part of wider income tax and inheritance tax planning.
- Full surrender and chargeable event gains – considering the timing of withdrawals, top-slicing relief and the potential income tax consequences.
I provide specialist advice to investors who already hold Utmost offshore bonds, helping them understand their options and structure withdrawals appropriately. Where more complex tax considerations arise, I also work alongside a Chartered Tax Adviser to ensure the wider tax implications are properly considered.
You can read my detailed article here, on Offshore Bond Withdrawal Advice: How to Avoid Unnecessary Tax
Considering an Utmost International Offshore Bond?
Whether you’re considering establishing a new Utmost offshore bond, reviewing an existing policy or exploring how an investment bond might support your family’s financial future, I would be delighted to help.
My work includes investment portfolio construction, retirement income planning, trusts, inheritance tax considerations and financial planning for internationally mobile families.
I offer an initial, no-obligation consultation to understand your circumstances and explain how I may be able to assist.
Arrange an Initial Consultation
Chartered Financial Planner & Chartered Investment Adviser | FCA-regulated advice through AES Financial Services Ltd
Interested in my view on RL360 bonds? Read that article here
Frequently Asked Questions
Is an Utmost International offshore bond a good investment?
An Utmost International offshore bond can be an appropriate investment structure for UK residents and internationally mobile individuals seeking tax deferral, investment flexibility and estate planning opportunities. However, its suitability depends on your circumstances, investment objectives, tax position and the overall charging structure. The bond itself is a tax and investment wrapper rather than a guarantee of investment performance.
What charges apply to an Utmost offshore bond?
Utmost offshore bond charges depend on the product and charging structure selected. They may include policy administration fees, investment charges, adviser fees and, in some arrangements, charges associated with an upfront commission. The total annual cost and any early surrender penalties should be clearly established before investing.
Can I establish an Utmost offshore bond without paying adviser commission?
Yes. Certain Utmost offshore bond arrangements can be established using a fee-based charging structure without an initial adviser commission being funded through the bond. This can significantly reduce costs and avoid the surrender penalties associated with some commission-based structures. The precise terms depend on the product and charging option selected.
Can I withdraw 5% annually from my Utmost offshore bond tax-free?
The annual 5% withdrawal allowance is tax-deferred rather than tax-free. UK policyholders can generally withdraw up to 5% of their original investment each policy year without an immediate chargeable event gain, with unused allowances carried forward, normally up to a cumulative maximum of 100% of premiums paid. Deferred gains may become taxable when the bond is subsequently surrendered or another chargeable event occurs.
Can I surrender my Utmost offshore bond without penalties?
This depends on the bond's original charging structure. Some commission-based arrangements include early surrender penalties, whereas other fee-based structures may have no contractual early surrender charge. Surrendering the bond can also create a chargeable event gain and a UK income tax liability, so both the product charges and tax implications should be assessed before proceeding.
Is it better to establish an Utmost bond on a life assurance or capital redemption basis?
Both structures can offer similar investment and tax-deferral benefits, but their duration and succession planning characteristics differ. A life assurance bond ordinarily terminates on the death of the final life assured, whereas a capital redemption bond can continue for its contractual term independently of anyone's lifetime. The appropriate structure depends on the intended ownership, estate planning objectives and how the investment may be passed to future generations.
Why does policy segmentation matter with an offshore bond?
An offshore bond can be established as a collection of individual policies or segments. Having sufficient segments can provide greater flexibility when making withdrawals, surrendering policies or assigning benefits to family members. The choice between partial withdrawals across all segments and surrendering whole segments can also produce materially different UK income tax outcomes.
Can I change financial adviser without surrendering my Utmost bond?
Yes. It is ordinarily possible to appoint a new financial adviser to an existing Utmost offshore bond without surrendering the investment. However, changing adviser does not automatically remove existing product charges or surrender penalties. A review can establish whether the existing arrangement should be retained, restructured where permitted, or replaced.
Can I get advice on an Utmost International offshore bonds if I live overseas e.g. UAE?
Yes, depending on your country of residence and the applicable regulatory requirements. I have more than 20 years’ experience advising internationally mobile individuals and families, including clients in the UAE. I can help assess existing offshore bond arrangements, investment strategy, charges and longer-term financial planning considerations. The availability and scope of regulated advice will depend on your jurisdiction.
Continue reading
Moving Back to the UK with a QROPS? Your Complete Guide
Returning to the UK after living overseas can raise a number of important financial planning questions, particularly if you hold pension benefits within a Qualifying Recognised Overseas Pension Scheme [...]
Thinking About Changing Your Utmost Adviser?
Thinking About Changing Your Utmost Adviser? If you hold an Utmost International investment bond and feel that your existing advice relationship is no longer meeting your expectations, it [...]
Been Recommended an Offshore Bond from RL360? Read This First.
Is an RL360 Bond the Right Fit for You? Here's What to Consider First If you’ve recently been recommended an offshore investment bond from RL360, it’s worth taking a [...]